


The global duty-free and travel retail market has reached a critical turning point of recovery and quality upgrading. cdf officially releases its 2025–2026 Consumption White Paper, systematically interpreting consumer trends, category evolution landscapes and the logic behind channel transformation, aiming to build industry-wide consensus and collaborate with all industry stakeholders to drive high-quality development in duty-free and travel retail.
Chapter 1 | The Duty-Free and Travel Retail Market Landscape
1. The Global Market: Passenger Traffic Rebounds as Regional Recovery Diverges
In 2025, international tourist arrivals grew by 4.0% year-on-year. The global duty-free and travel retail market continued its recovery, with market size reaching USD 75.9 billion, up 2.4% year-on-year.
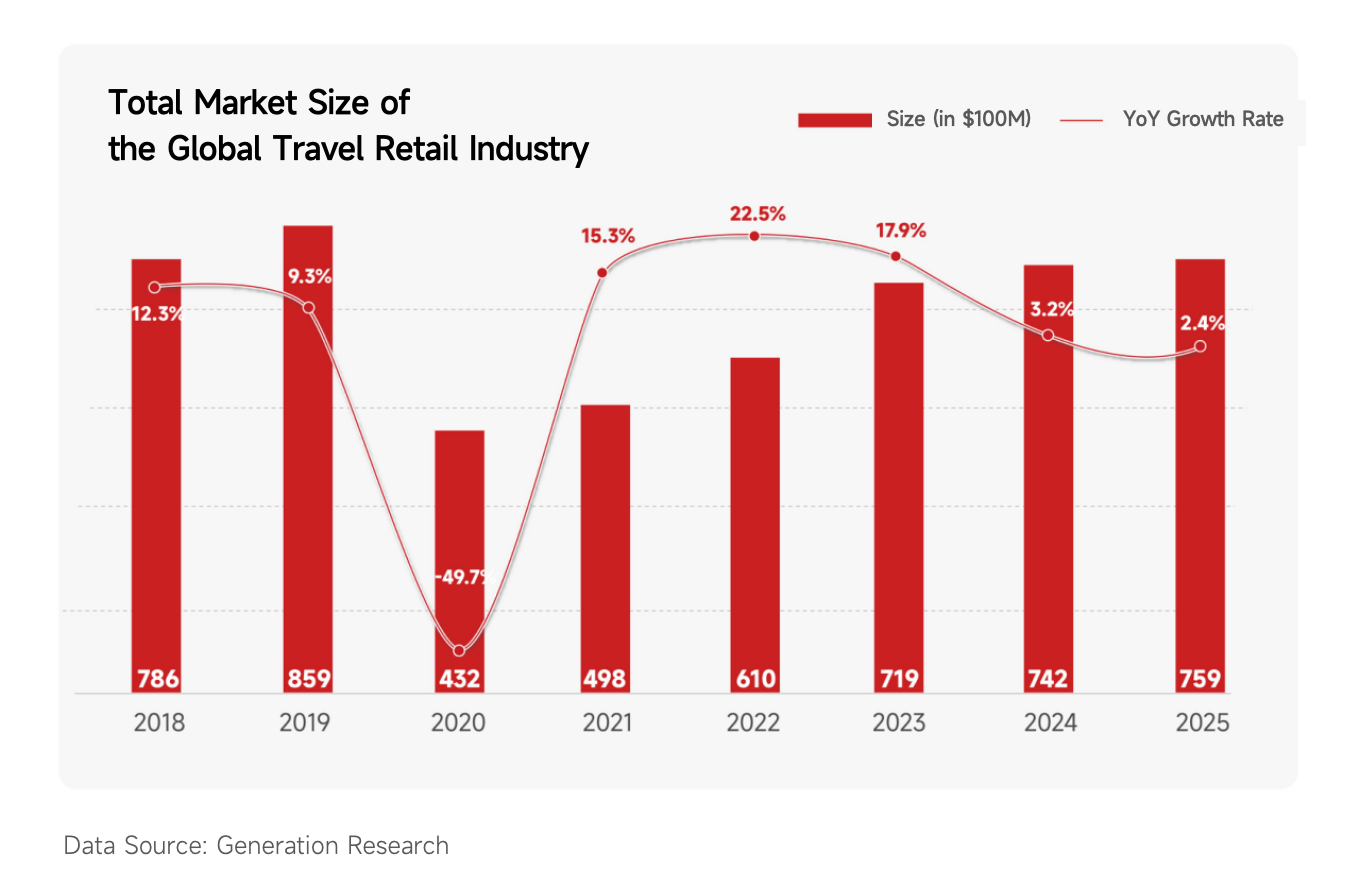
Against the backdrop of overall recovery, regional performance diverged: the Asia-Pacific region accounted for 40.2% of the global market, firmly securing its position as the core of the market; leveraging a mature network of transport hubs, Europe upgraded travel retail scenarios, achieving 7.0% year-on-year growth; the Middle East and Africa, buoyed by cultural and tourism infrastructure development and visa facilitation, became new growth frontiers.
2. The Chinese Market: A Trio of Consumption, Tourism and Policy Dividends Fortifies Growth Certainty
Consumption fundamentals remain solid with ample momentum. Household incomes and consumer willingness to spend are steadily growing: in 2025, per capita disposable income rose by 5.0% year-on-year, and the consumer confidence index has posted positive year-on-year growth every month since May 2025.
In 2025, total domestic trips and domestic tourism spending both exceeded 2019 levels. Hainan has entered a new phase with visitor volume exceeding 100 million and total visitor spending surpassing RMB 200 billion; domestic outbound demand was simultaneously unleashed. Mainland residents made 170 million outbound trips in 2025, up 15.1% year-on-year; the total number of inbound foreign visitors reached a historic high, injecting new momentum into China's duty-free and travel retail market.
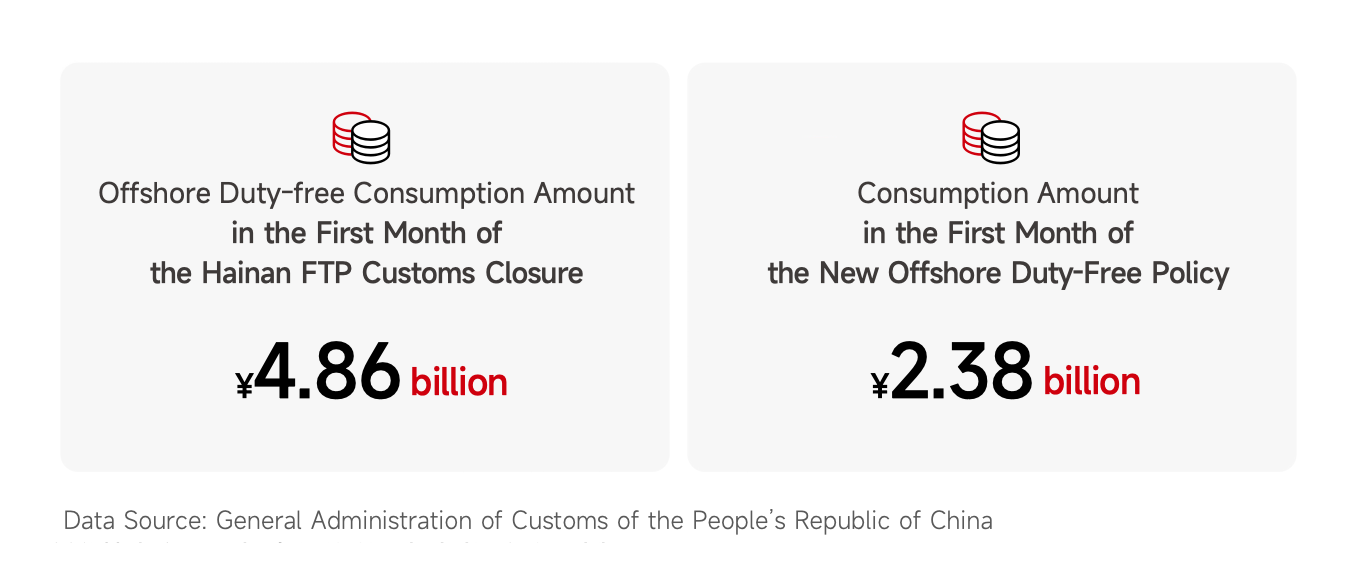
Hainan's customs closure operation and the new offshore duty-free policy were implemented successively, driving growth in Hainan's offshore duty-free consumption across passenger traffic expansion, category enrichment and experience upgrading. In the first month of the customs closure operation, consumption grew by 46.8% year-on-year; in the first month of the new policy implementation, consumption grew by 27.1% year-on-year.
Chapter 2 | A Panoramic Insight into Duty-Free and Travel Retail Consumers
1. New Consumption Patterns: K-Shaped Divergence, Deepening Experiential Value, and AI-Driven Decision-Making Chains
Driven by divergent consumption expectations, upgraded consumption philosophies and breakthroughs in AI technology, three major new consumption trends are emerging:
1.1 K-Shaped Divergence: High-End Resilience and Middle-Class Rationality
China's consumer market is exhibiting a clear K-shaped trajectory: high-net-worth customers on the upper segment of the K-curve remain resilient in consumption, while the middle-class group on the lower segment returns to rationality. "Pragmatism" and "savvy spending" have become stable lifestyles.
1.2 Experience First: "Emotional ROI" Emerges as the Core Consumption Benchmark
As national consumption philosophy upgrades, consumers are placing greater value on emotional value and the quality of experiences. "Emotional ROI" is replacing "value for money". Expectations for experiential value diverge sharply by each consumer segment: high-net-worth customers seek exclusive premium services, middle-class customers value the atmosphere of physical shops, and various interest-based groups expect immersive experiential spaces that enable deep engagement.
1.3 AI-Driven Reshaping of Decision Chains: From Search-Based to Conversational Models
AI is permeating the entire consumer decision-making journey. 64.0% of Chinese consumers have utilised AI tools in their latest luxury purchases, with AI transitioning from a "supportive aid" to a "default path". This is pushing retailers to accelerate their AI tool deployments to lift consumption conversion efficiency.
2. Panoramic View of the Industry's Customer Base: Active High-Tier Members, Expanding Lower-Tier Markets and Rapid Growth in Foreign Visitors
The duty-free and travel retail customer base is steadily expanding. As a leading global travel retailer, cdf saw its user base grow by 19.5% year-on-year in 2025, with membership reaching 62 million by July 2026. Meanwhile, the customer structure continues to evolve:
2.1 High-Tier Members Remain Active, Underpinning the Industry's Spending Base
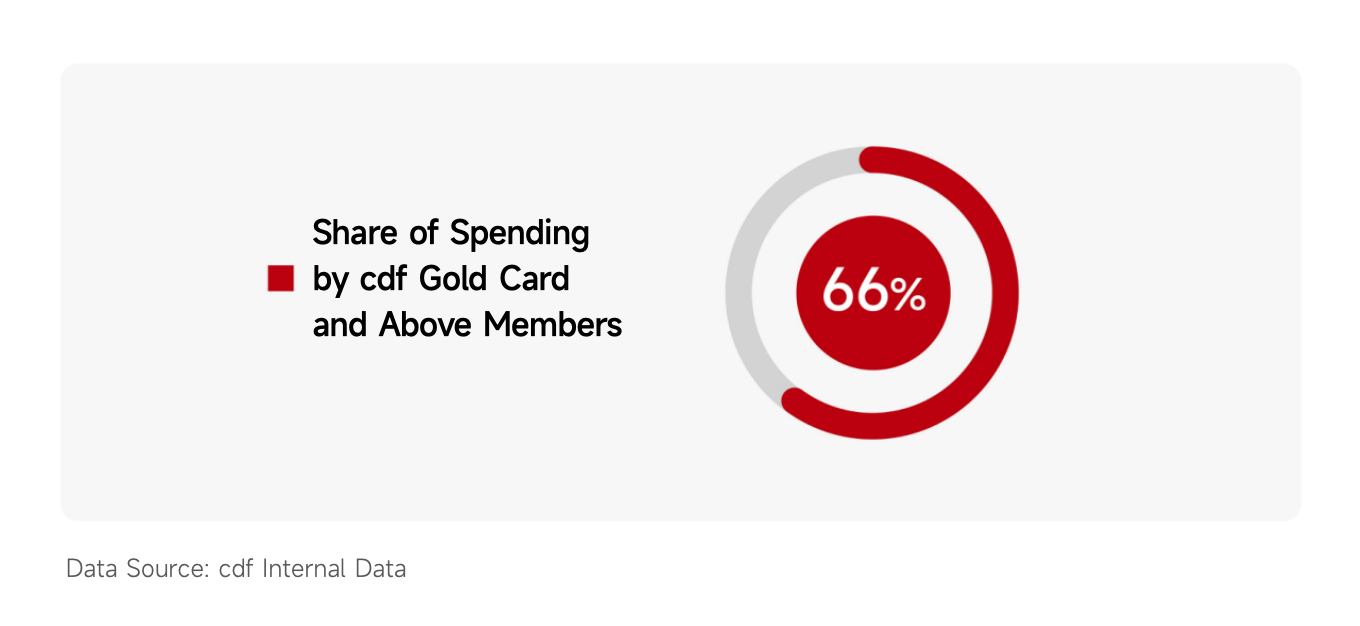
High-tier customers have consistently been the main spending force in the duty-free and travel retail market, with outstanding spending power and stable repeat purchases. Within cdf's member base, the number of Gold Card and above members grew 12.1% year-on-year, and the number of customers with annual spending of over RMB 50,000 also continued to grow.
2.2 Lower-Tier Market Penetration Accelerates, Becoming a New Source of Industry Growth
As travel demand among residents of lower-tier cities is released, and with travel retailers moving operations online, the customer base continues to expand into lower-tier markets. cdf added nearly 15 million new users in 2025, and new members from Tier 3 and below cities more than doubled year-on-year.
2.3 Foreign Travellers’ Spending Heats Up, Unlocking Inbound Consumption Potential
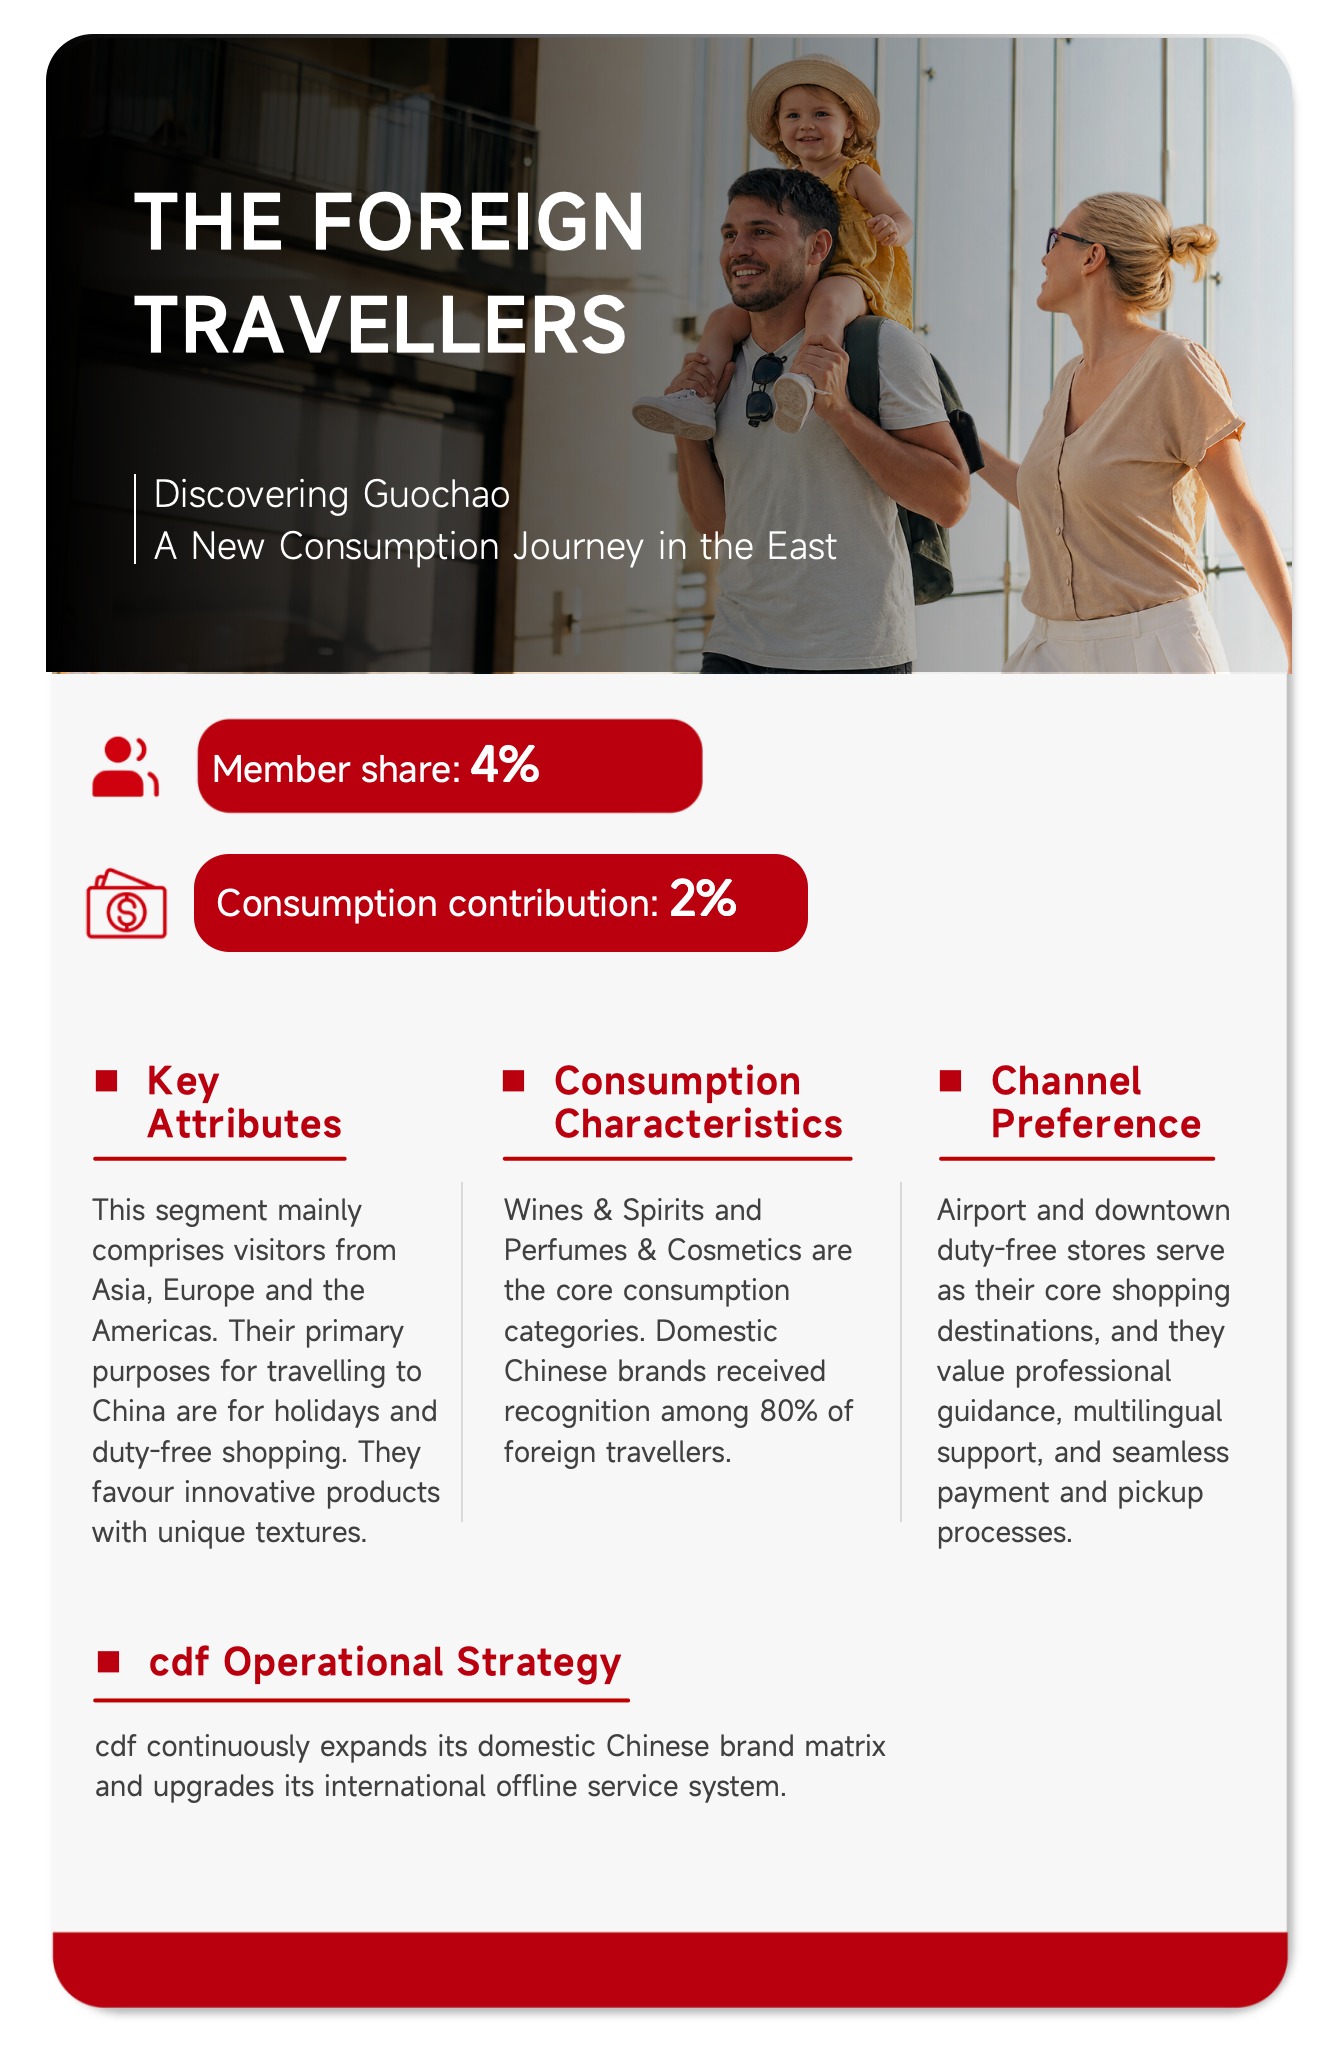
As cross-border travel returns to normal, foreign customers have become a new growth engine for travel retail. In 2025, cdf's foreign users grew 41.5% year-on-year, far outpacing the growth in total foreign arrivals nationwide, and foreign repeat purchasers grew 48.7% year-on-year.
3. cdf's Nine Customer Segment Personas: Member Operations from "Traffic Coverage" to "In-Depth Value Cultivation"
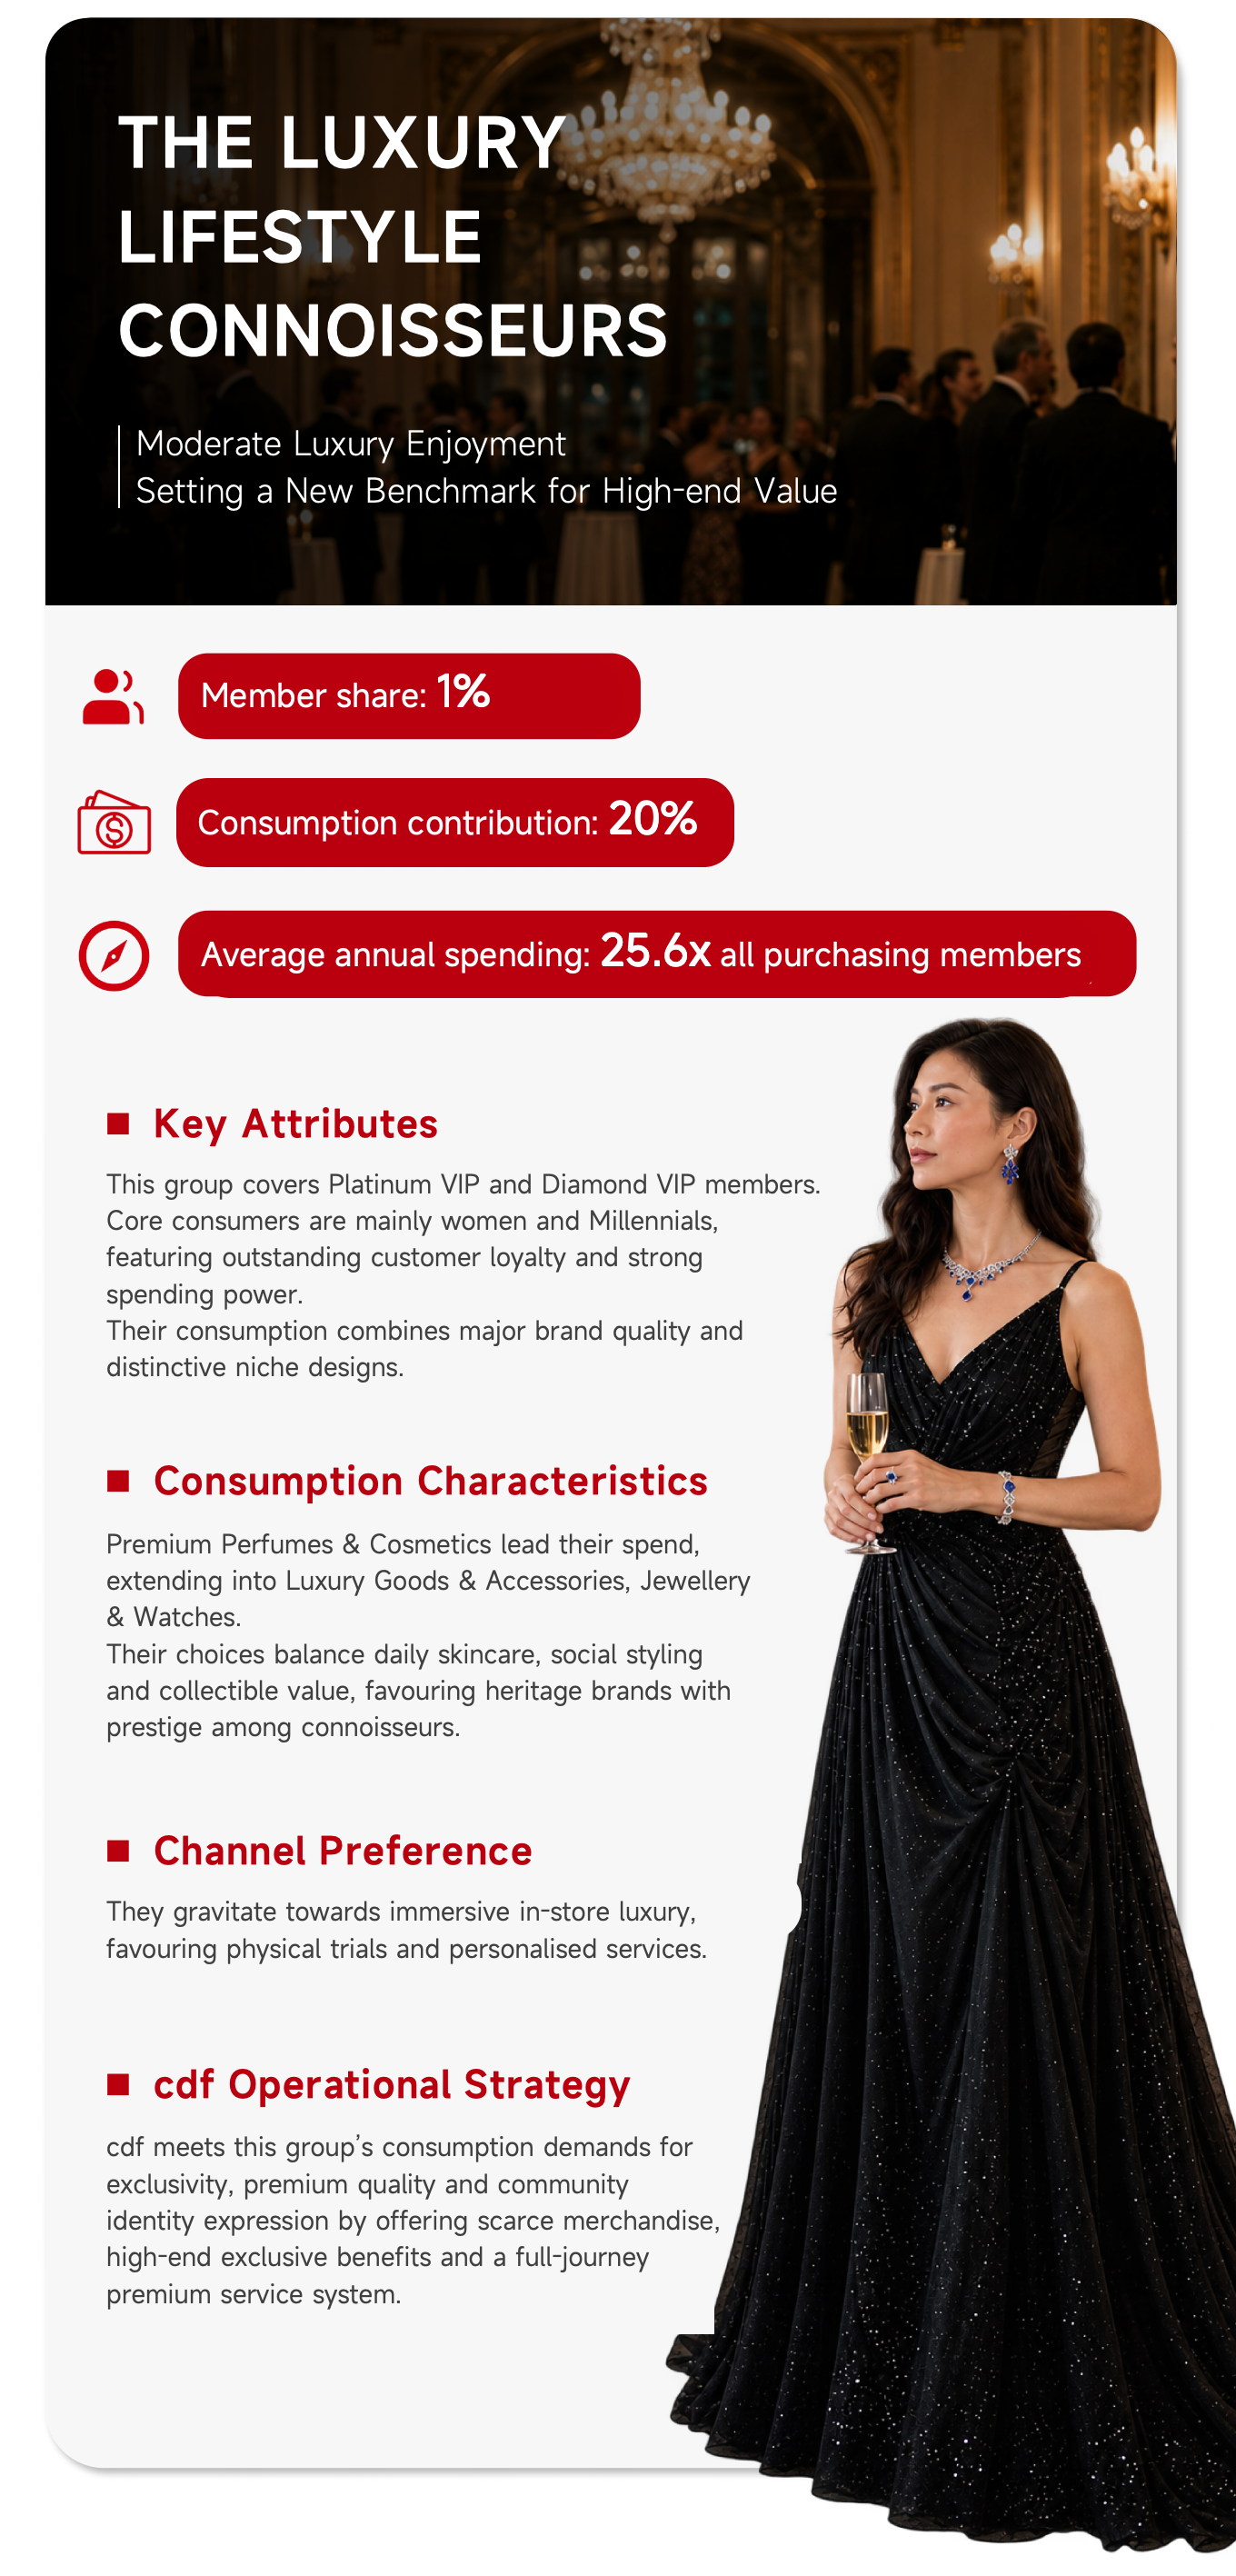
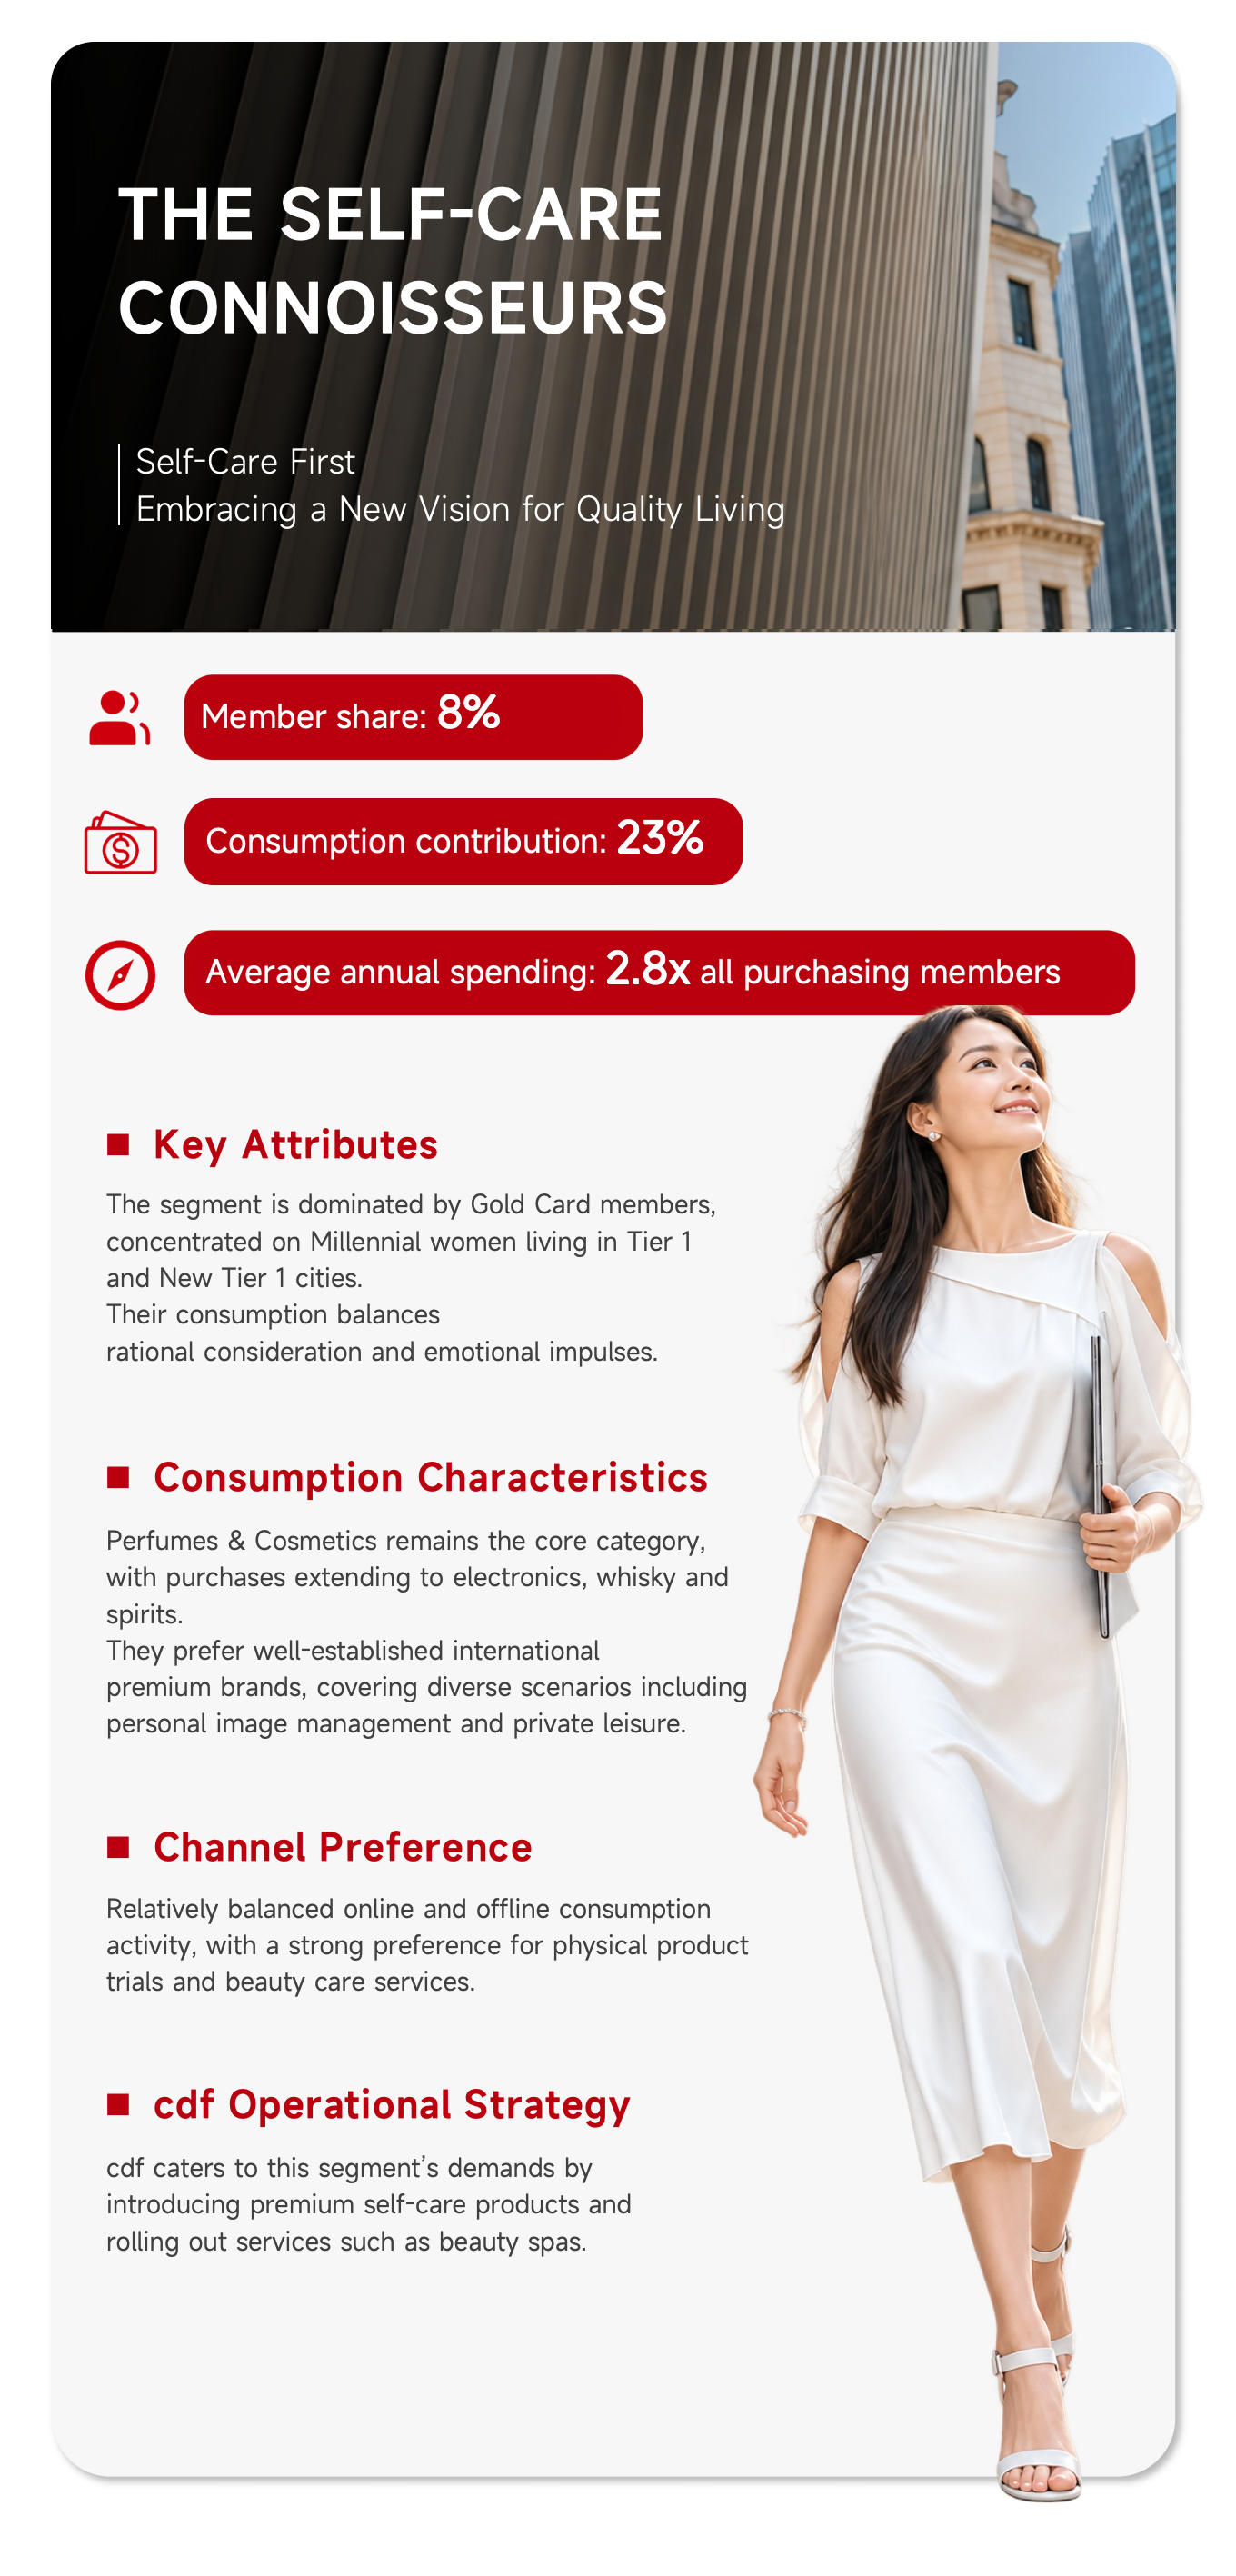
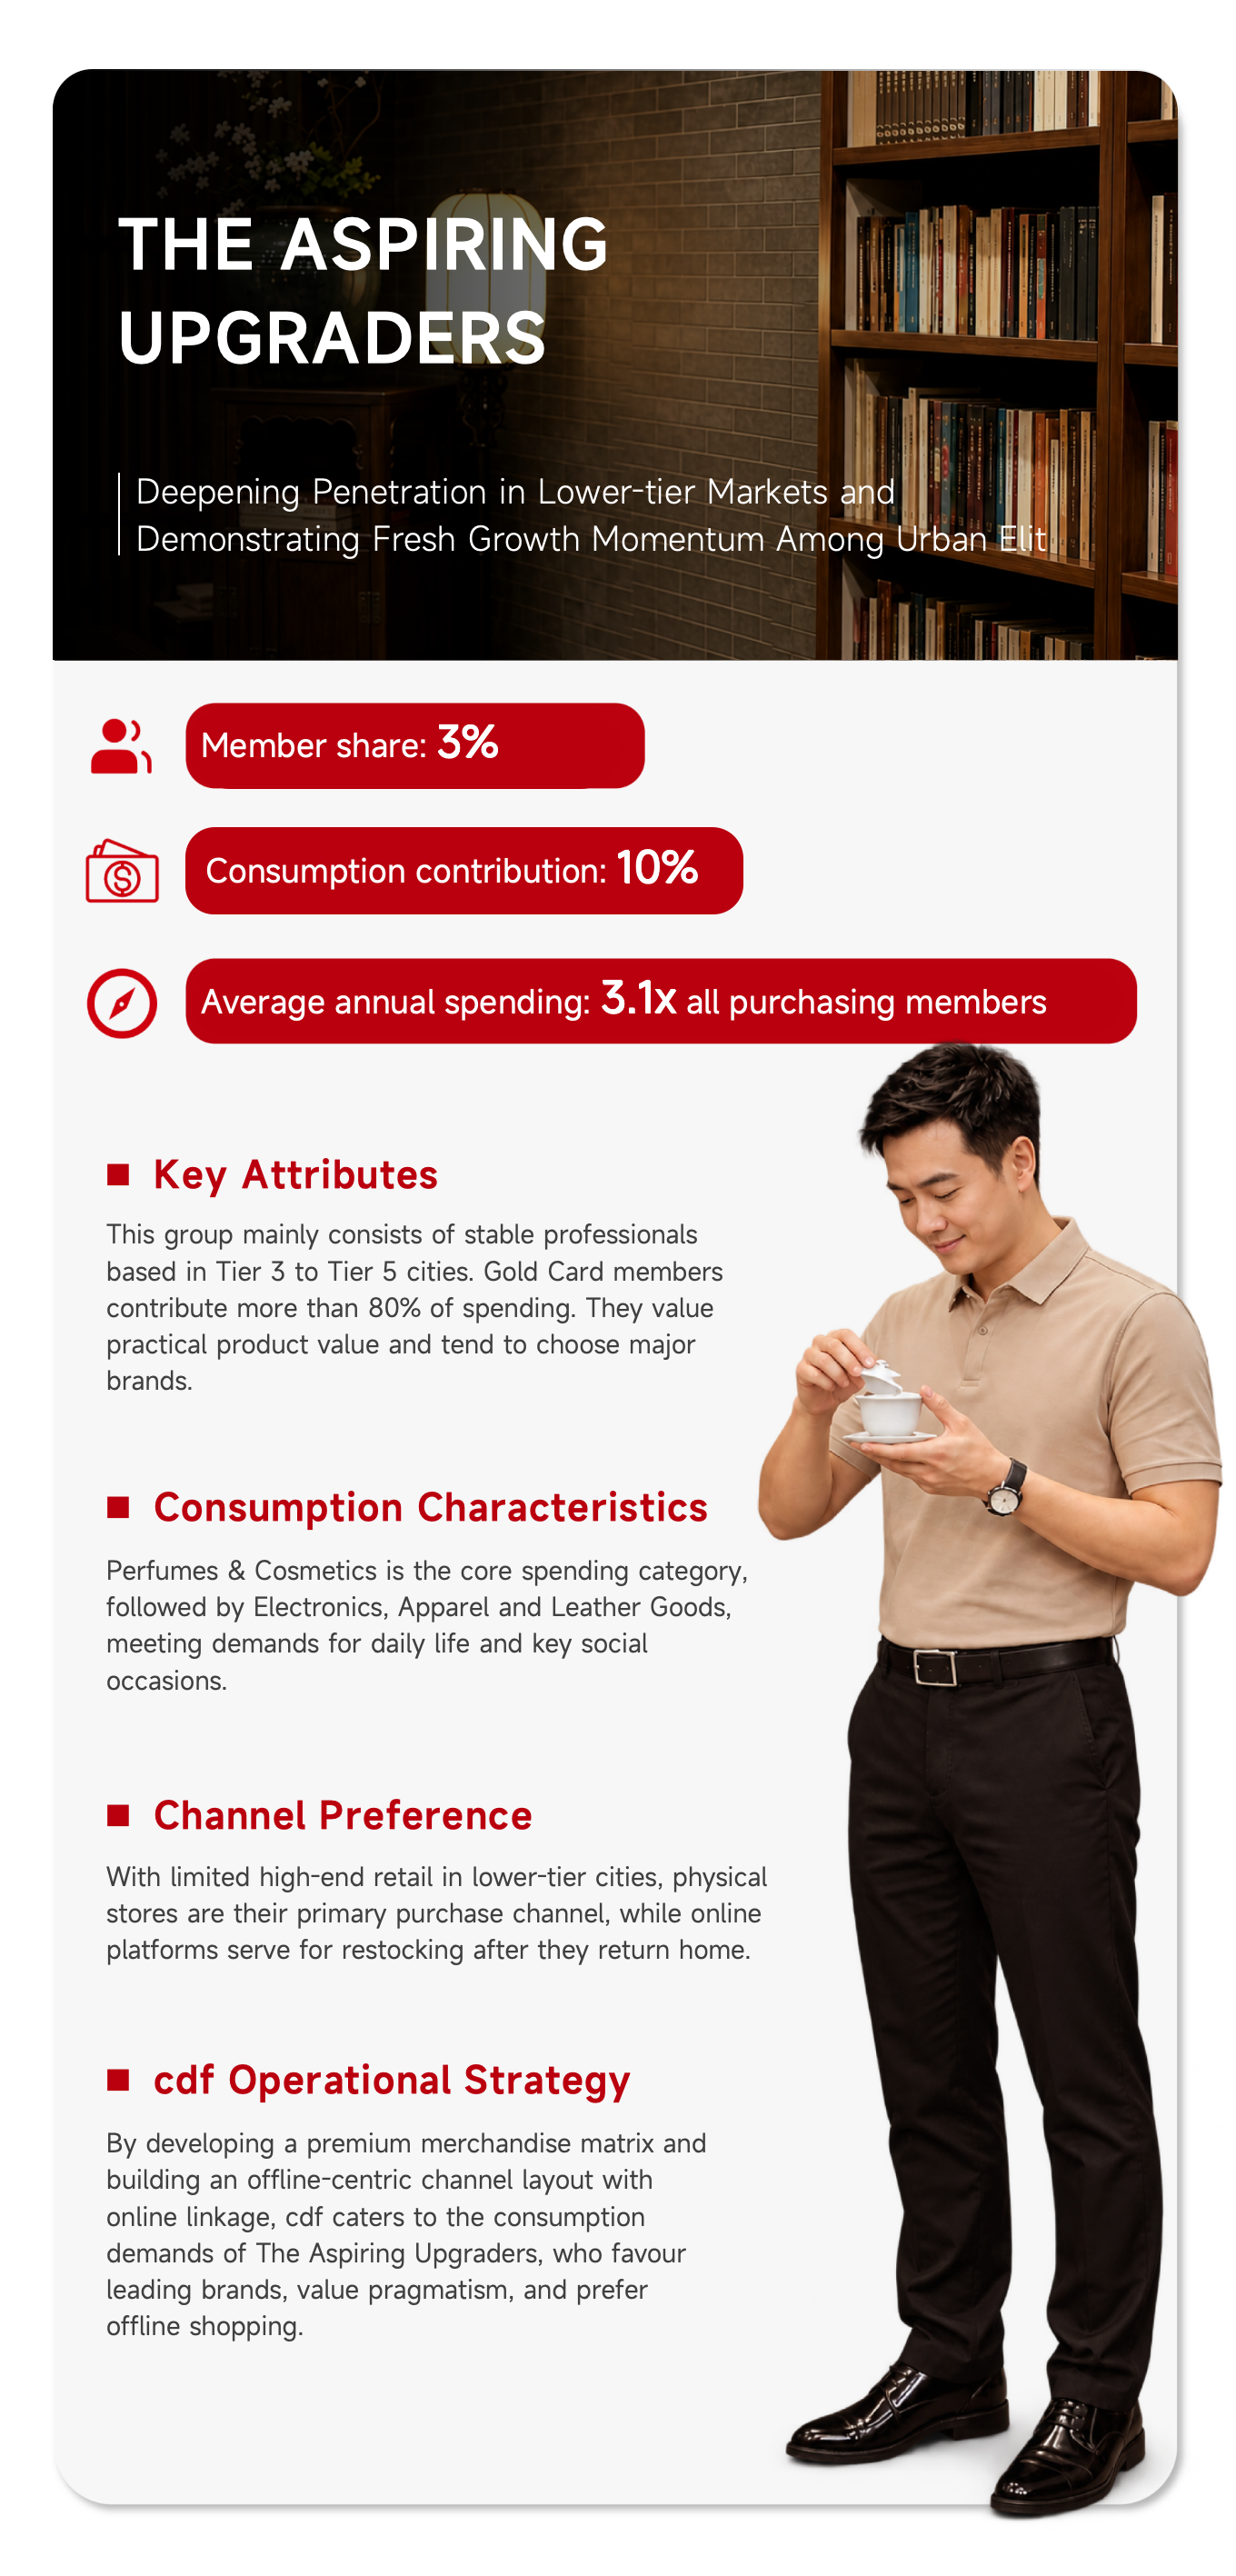
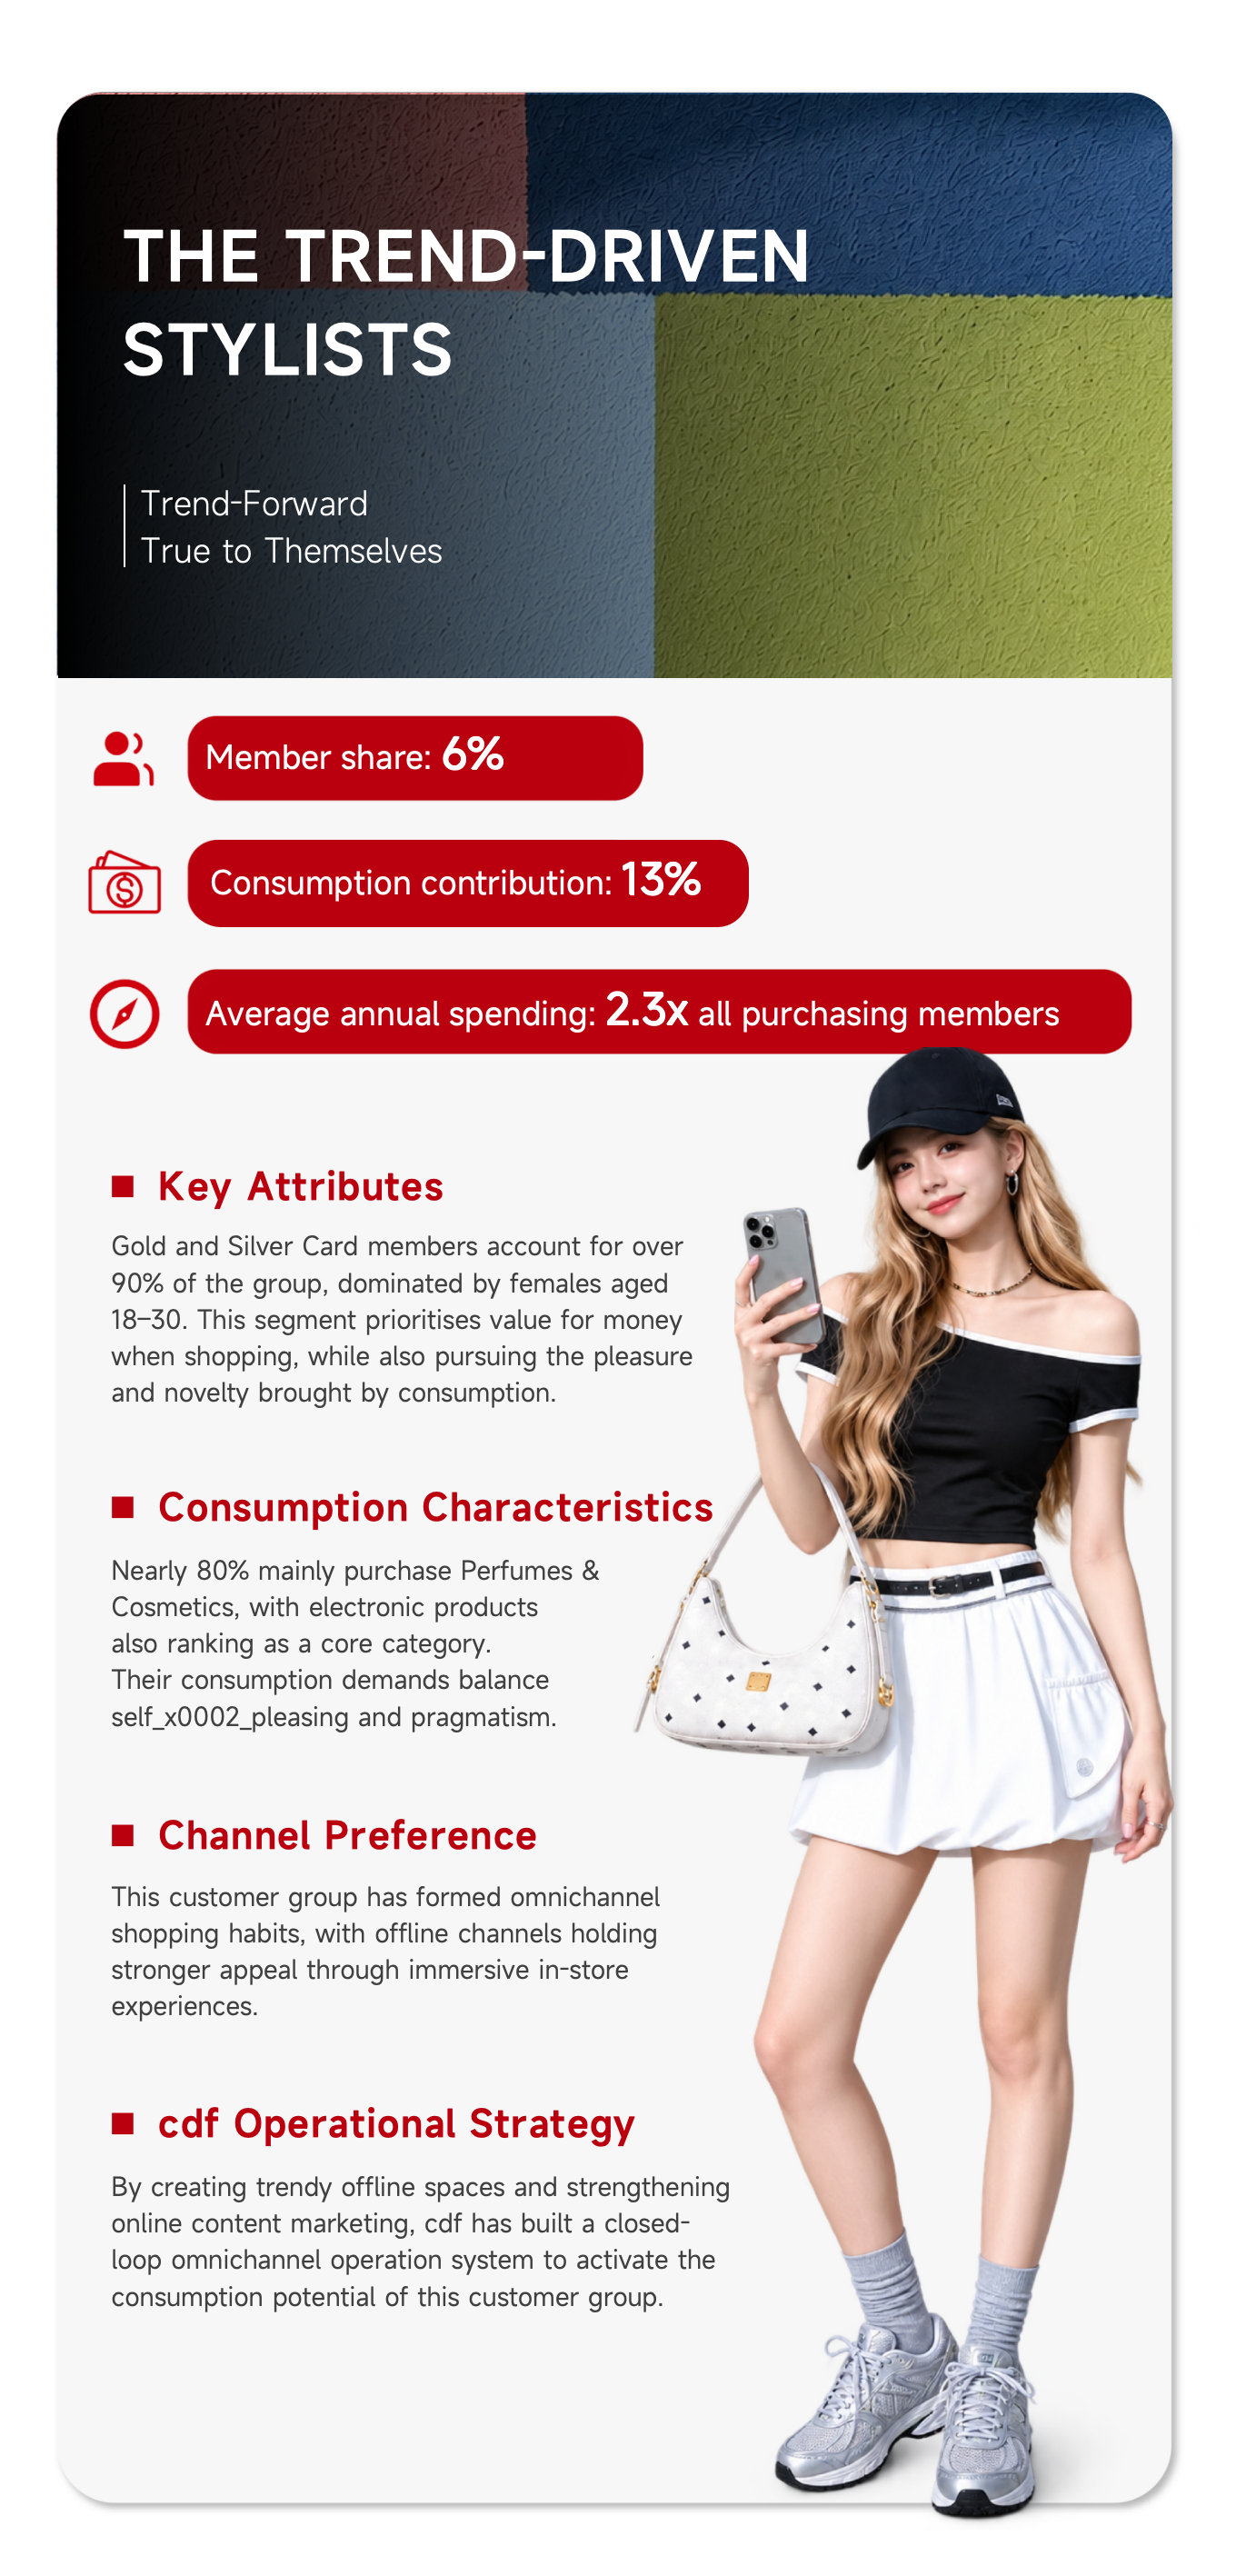
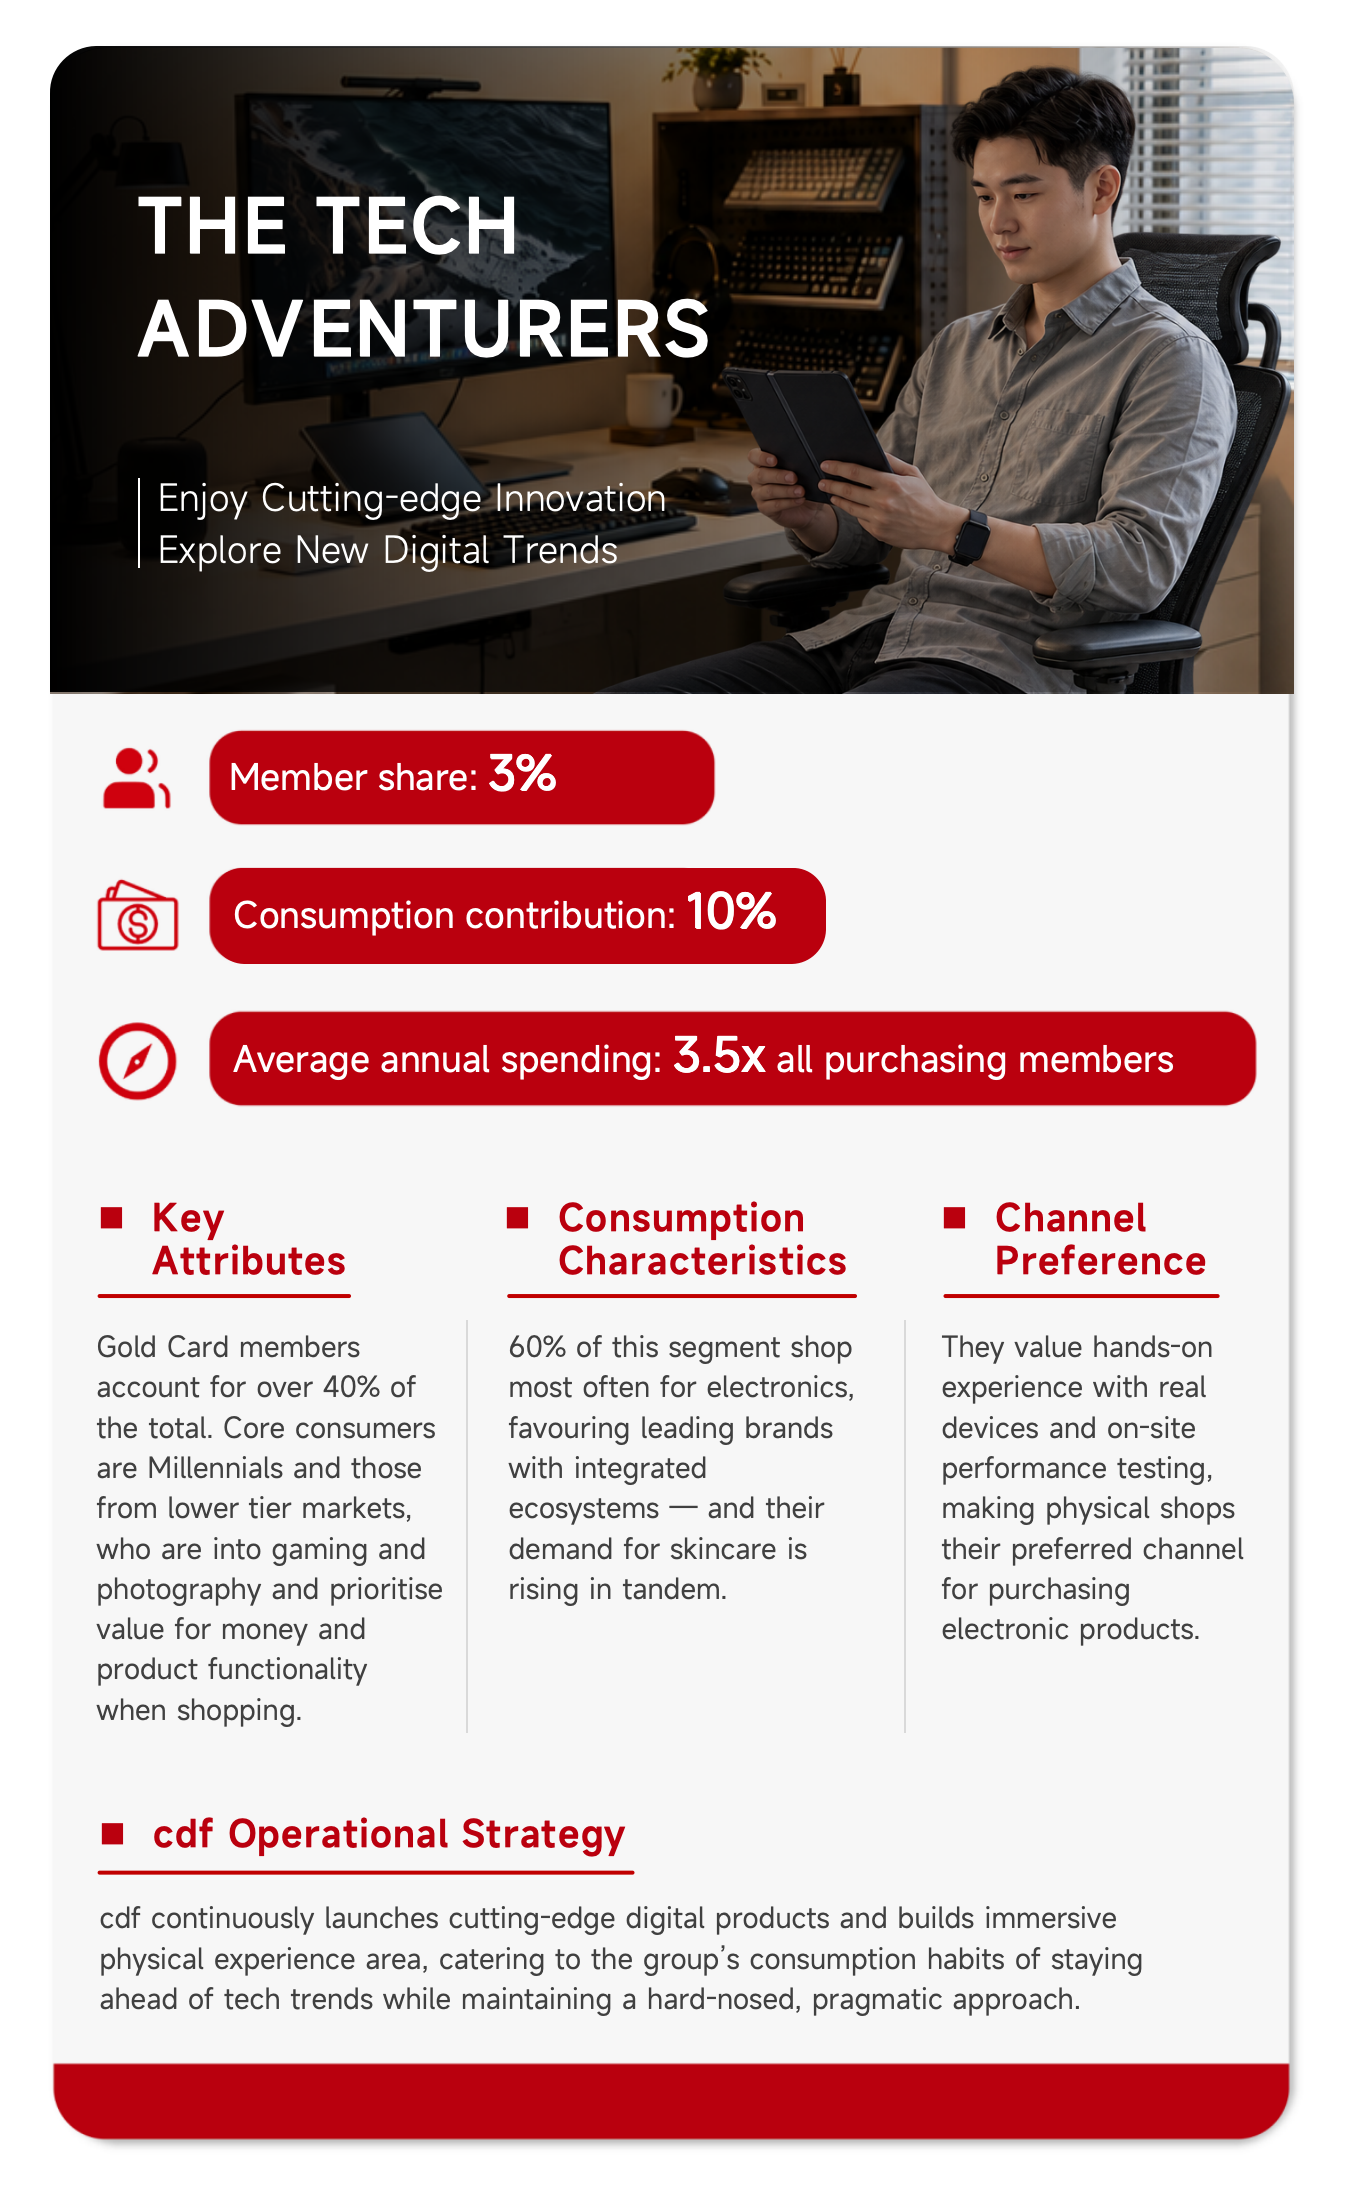
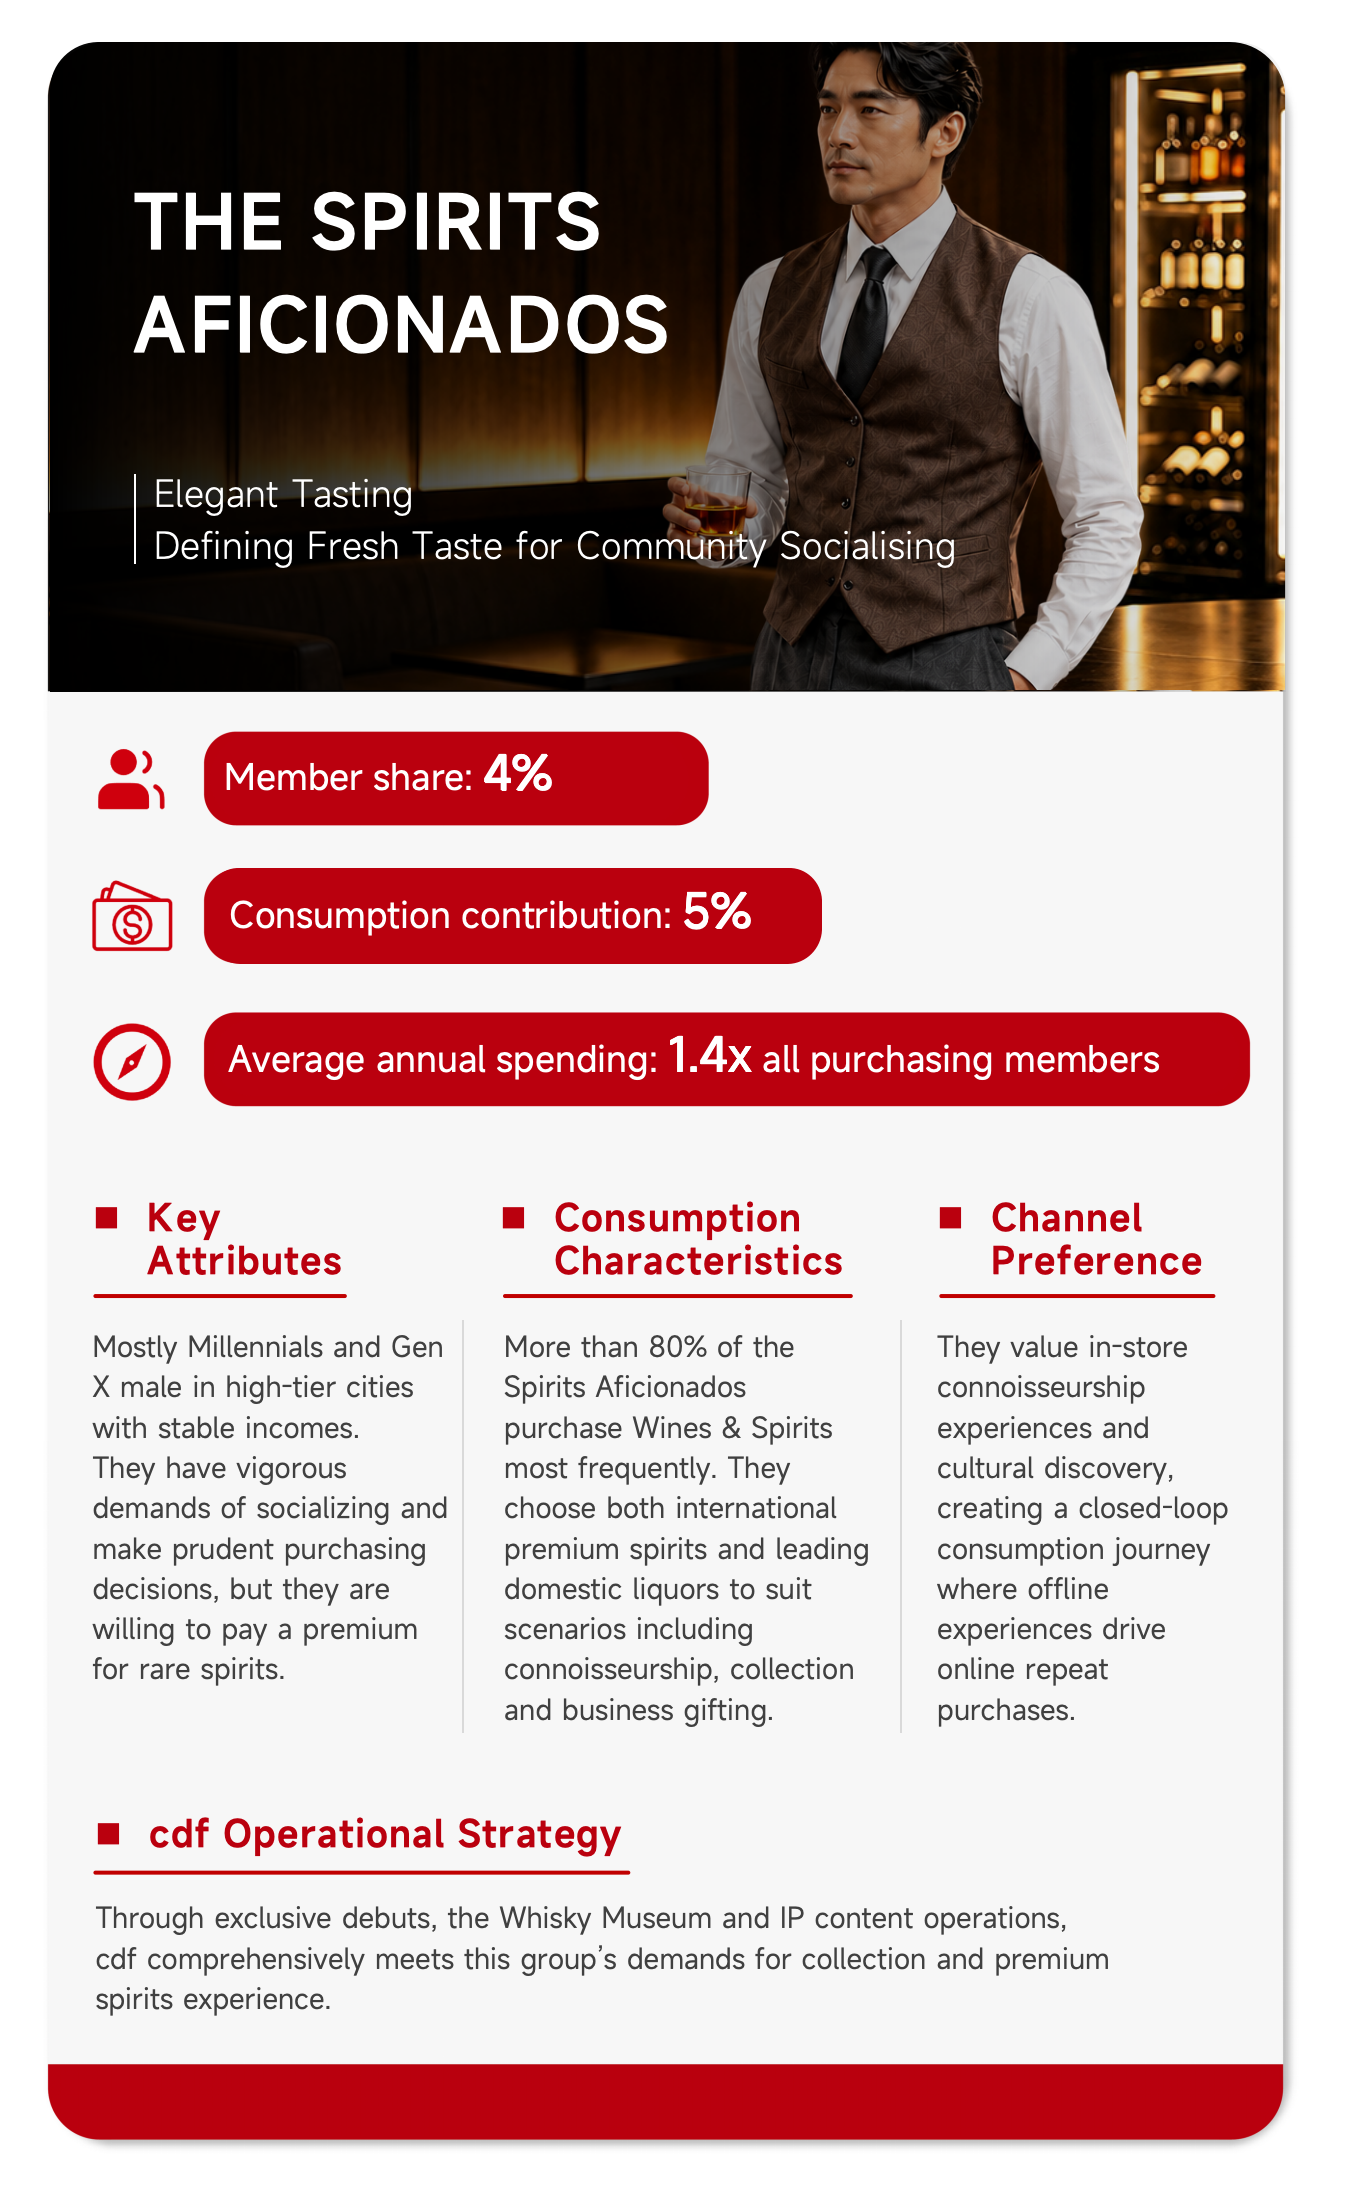
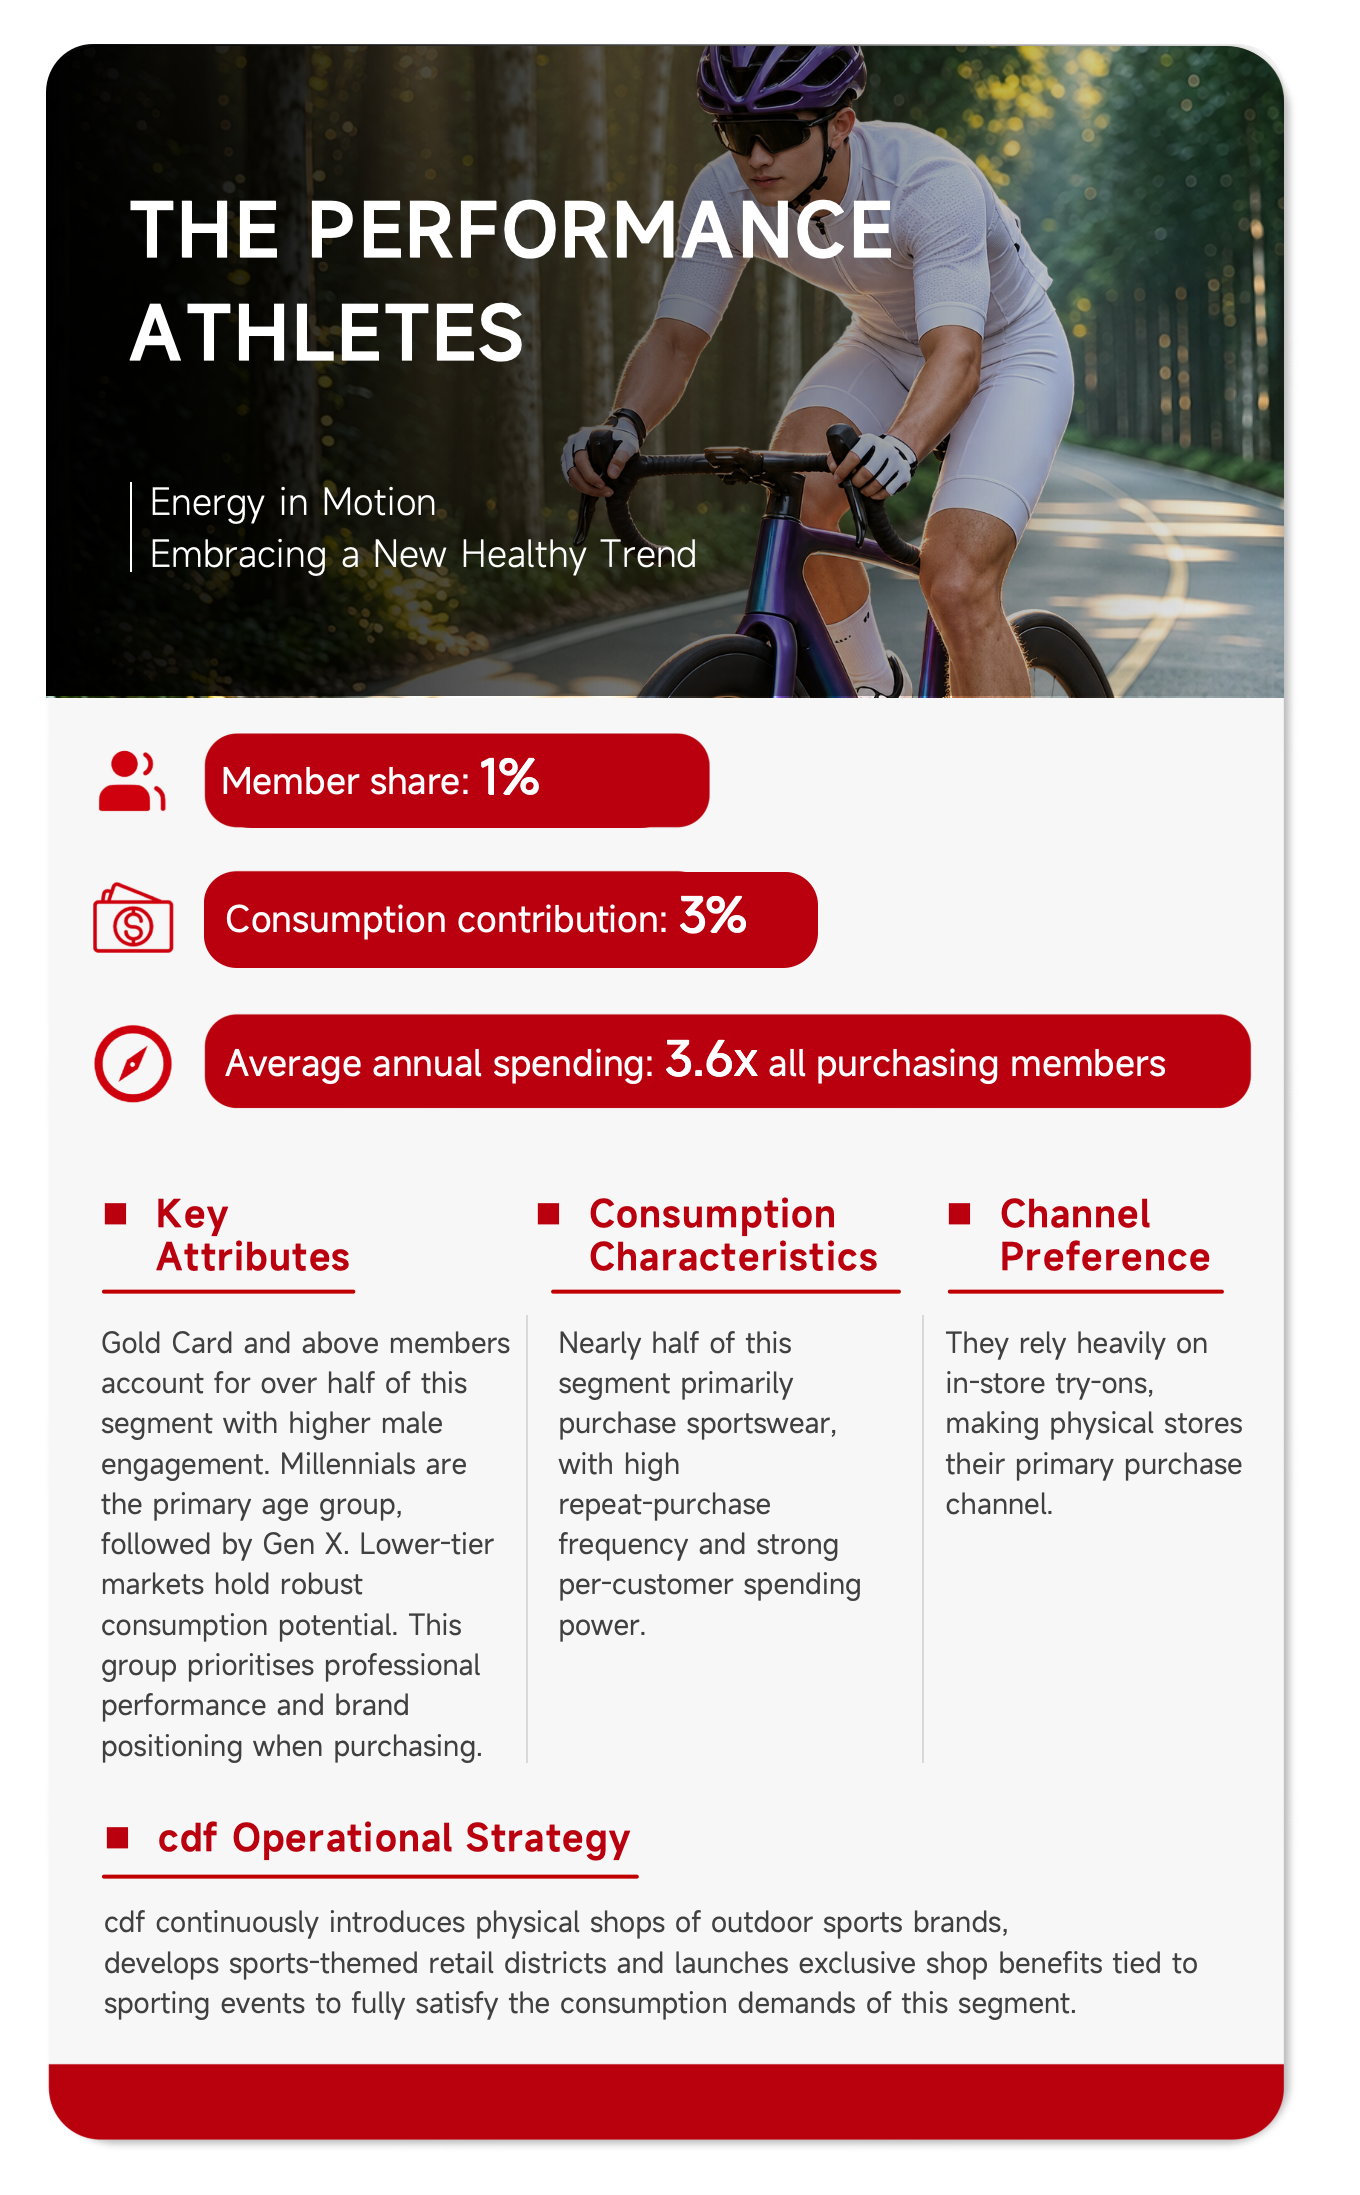
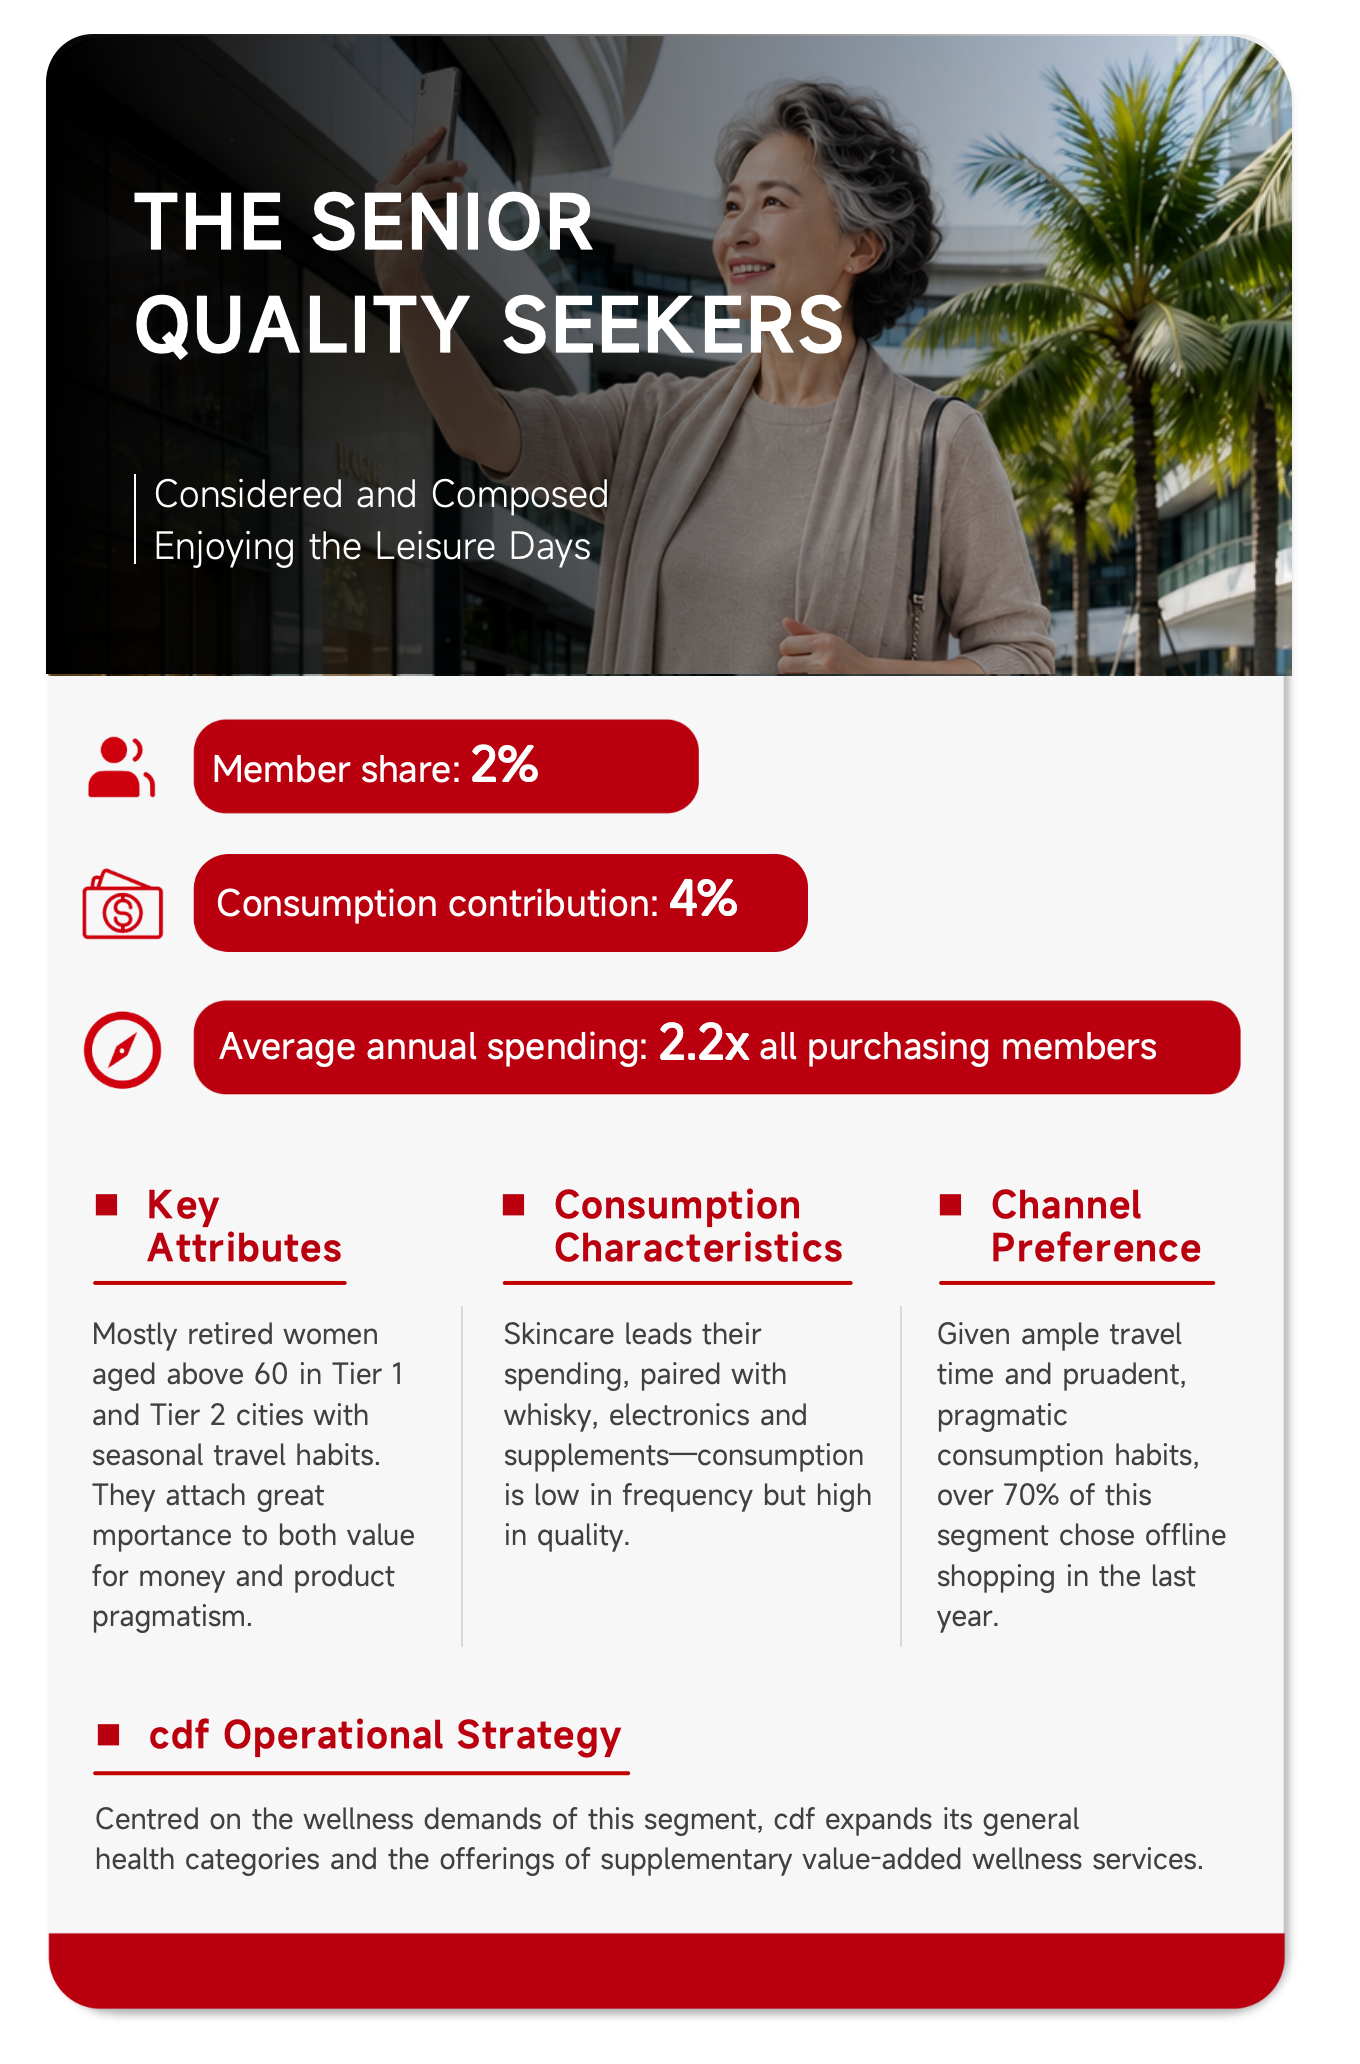
cdf carried out refined segmentation based on members' ages, locations, membership tiers, spending amount and category consumption in 2025, constructing a system of nine customer segments. The nine segments account for 27% of all shopping members and 74% of total spending.
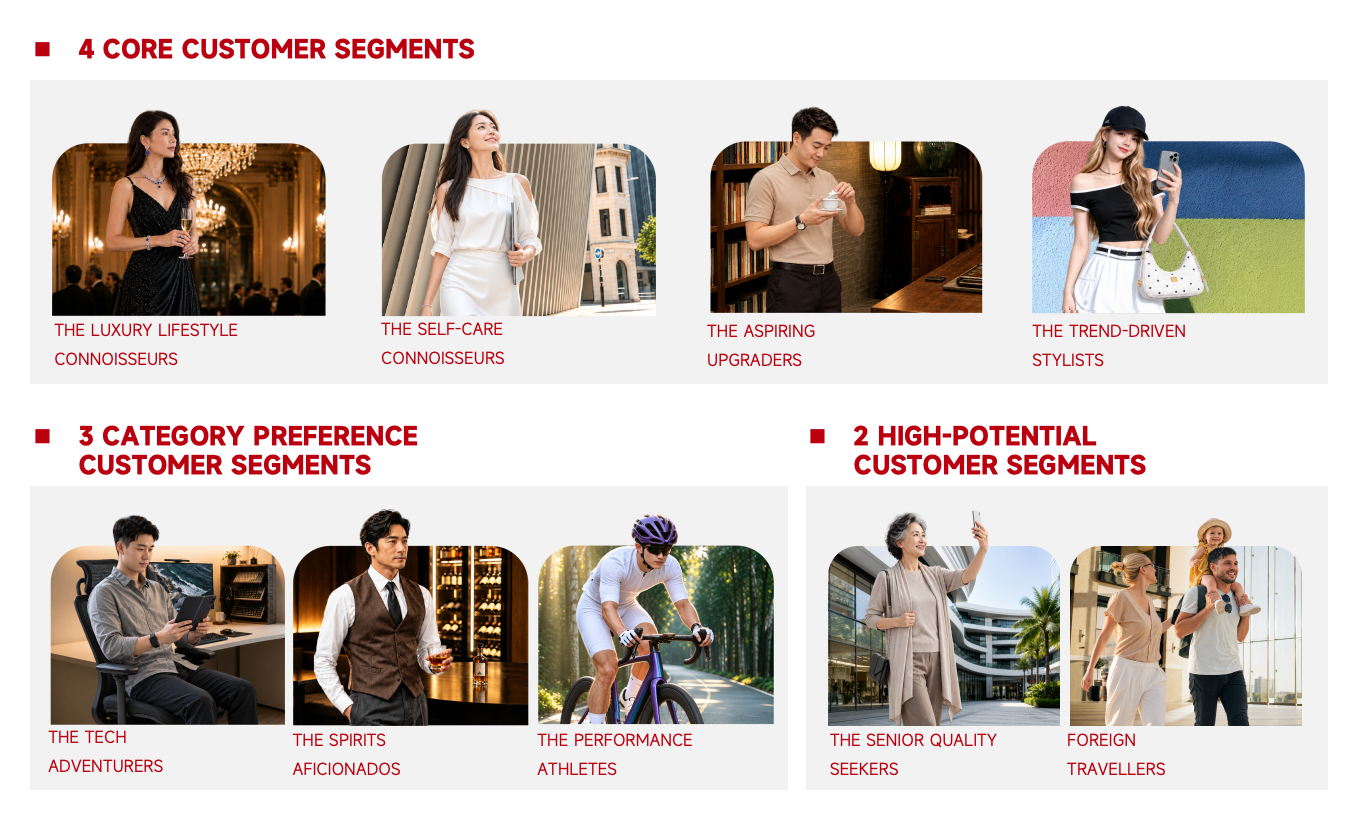
4 Core Customer Segment Personas
3 Category Preference Customer Segment Personas
2 High-Potential Customer Segment Personas
Chapter 3 | Duty-Free and Travel Retail Category Trends and Practices
1. New Category Trends: Structural Optimisation, Scarce Merchandise Supply, and Private Label Layout
At this stage, consumer preferences, brand channel strategies and travel retailers' operating philosophies continue to evolve, fostering a series of new category development features:
1.1 Perfumes & Cosmetics Continues to Anchor the Business, with Multi-Category Growth Driving Structural Optimisation
According to Generation Research data, in 2025 Perfumes & Cosmetics accounted for 32.2% of sales, firmly securing its position as the pillar category of global duty-free and travel retail. Meanwhile, Food & Beverage, Fashion Accessories, Electronics, and Wines & Spirits all achieved positive growth. In 2025, the government also introduced multiple policies to support the expansion of duty-free merchandise scope, strongly driving the diversification of duty-free categories.
1.2 New Product Launches and Limited Editions Are Concentrating in Duty-Free Channels
Leveraging the advantages of high-net-worth customer aggregation and premium consumption scenarios, duty-free channels have become the core platform for brand new product launches and exclusive limited-edition releases. During the "2026 Global Delight Season", cdf partnered with Qeelin to launch an exclusive Hulu collection, while DFS's New York airport store released Maker's Mark New York City limited-edition bourbon whisky.
1.3 Private Label Layout Becomes a New Lever for Category Innovation
To enrich the merchandise system and optimise profit structure, travel retailers have begun exploring private label development as an important vehicle for category innovation. Domestically, cdf has launched private brands covering beauty and health categories; internationally, Avolta has created the regional IP "Exploring Canada", targeting characteristic North American consumption scenarios.
2. cdf Expands Category Value Boundaries Through Diversified Innovation
Aligning with industry trends, cdf advances the expansion of high-potential categories, the introduction of exclusive merchandise, and the incubation of private labels, while fully leveraging channel advantages to support Guochao (China Chic) Going Global, and improving category supporting services to optimise the consumer shopping experience.
2.1 High-Potential Category Expansion
cdf has laid out high-potential categories including fragrances, gold, lab-grown gemstones/diamonds, outdoor sports, health foods and low-alcohol beverages. Following the gold tax reform policy, cdf has actively promoted the entry of brands such as LAOMIAO into Hainan's offshore duty-free channel.
2.2 Exclusive Merchandise Matrix Development
cdf collaborates with brands to release exclusive limited editions and new product debuts, and has landed the exclusive sales brand Diptyque in the Hainan region, building competitive moats through scarcity.
2.3 Private Label Incubation
Leveraging its global supply chain and "central SOE standard" quality control system, cdf has launched private brands including cdf Beauty and cdf Health in the fields of Perfumes & Cosmetics, health and wellness, and cultural creativity, marking cdf's extension toward the role of a brand owner.
2.4 Guochao Going Global
Leveraging overseas operating experience to support Guochao Going Global, cdf has partnered with ANTA to expand the duty-paid retail market in Cambodia. In addition, cdf has secured exclusive distribution rights for 52TOYS in Hong Kong, China, connecting with 1,500+ retail points in Hong Kong and Macao, upgrading from a channel retailer to a brand agent.
2.5 Category Service Extension
cdf has rolled out supporting services such as "1-Point Makeover" and "1-Point Drink" around categories including colour cosmetics and spirits, and has landed innovative scenarios such as brand duplex shops, pop-up/long-running pop-up stores, and the "Whisky Museum", breaking through the single sales scenario of offline shops in multiple dimensions.
3. cdf's Five Core Categories Develop in Coordination, Forming a Multi-Layered Growth Pattern
In 2025, cdf's core category structure was clear, with differentiated growth across categories. Perfumes & Cosmetics accounted for over half of cdf's sales, continuing to play the anchor role; Jewellery & Watches and Luxury Goods & Accessories relied on premium merchandise to drive spending per customer and reinforce channel premium positioning; Food & General Merchandise achieved rapid sales growth, becoming a key category for expanding consumption scenarios and driving repeat purchases; Wines & Spirits catered to self-consumption, gifting and collection needs, continuously empowering merchandise matrix diversification.
3.1 Perfumes & Cosmetics
Skincare anchors the category base with stable repeat purchases. Leveraging "self-reward consumption" and "olfactory consumption", colour cosmetics and fragrances are releasing stronger growth momentum. High-net-worth women are the core consumer group, while the brand matrix is expanding toward domestic brands and service experiences are upgrading toward premiumisation.
Skincare remains at the core, with colour cosmetics and fragrances demonstrating outstanding growth potential. Skincare accounts for over 70% of category sales and exhibits stable repeat purchase characteristics; colour cosmetics and fragrances, leveraging self-reward consumption, are growing significantly faster than the overall category.
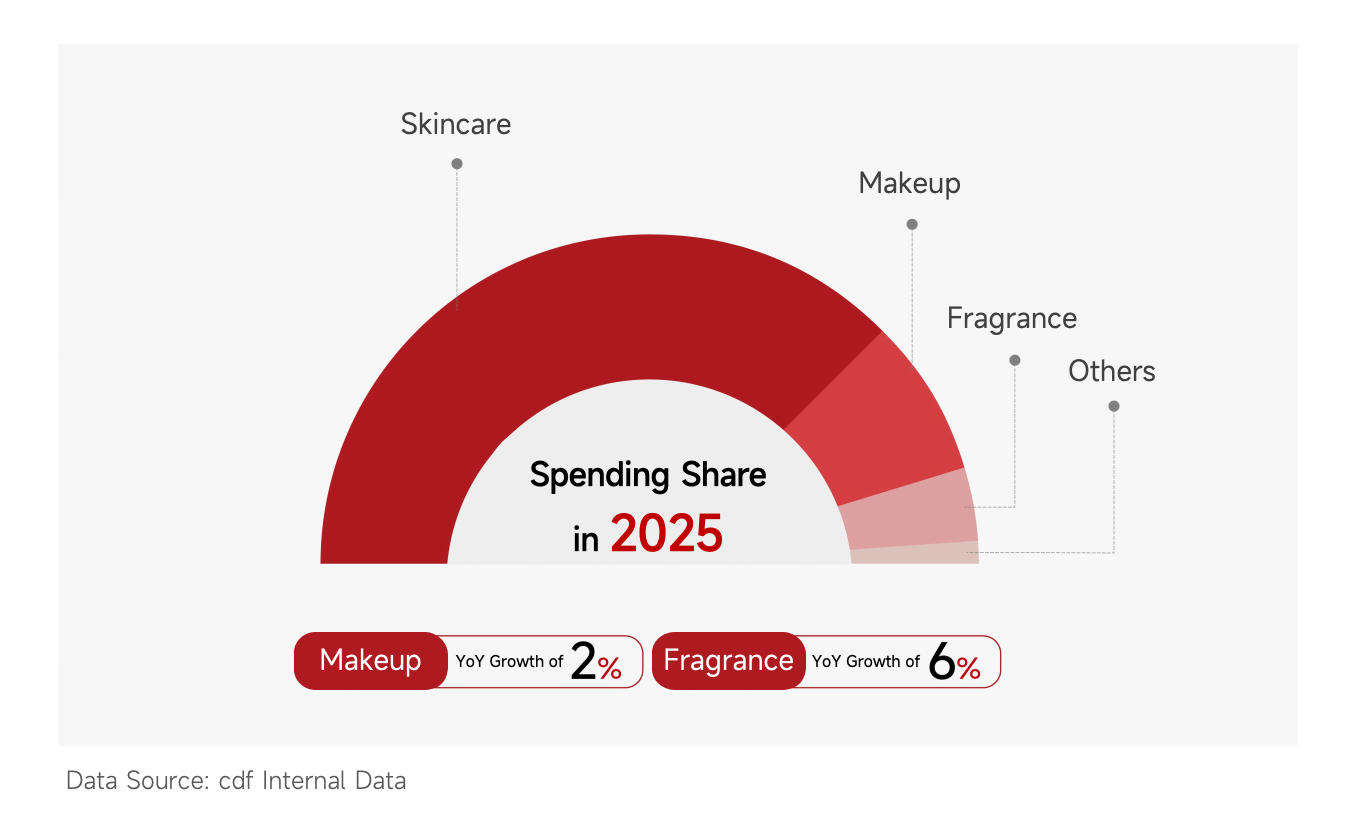
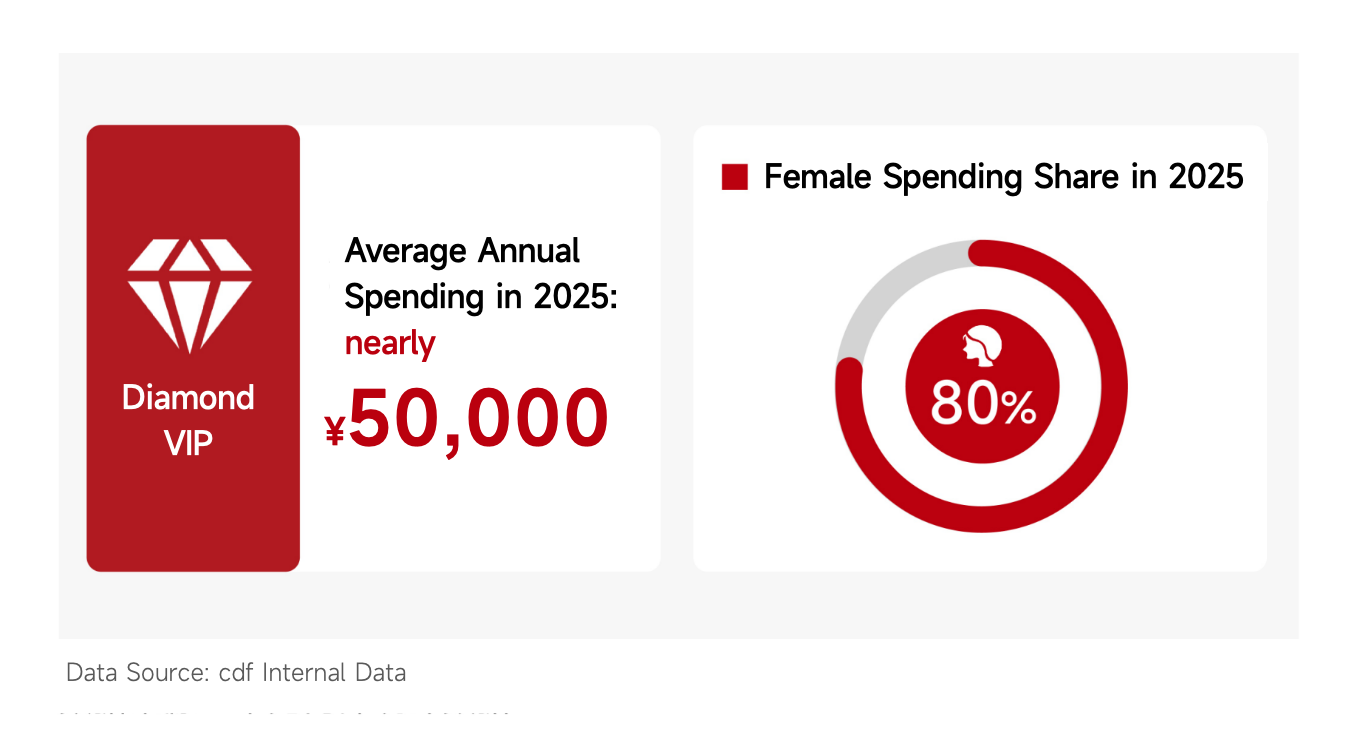
Gold Card and above members and women are the main consumption force, while men, Gen X and lower-tier markets constitute diverse growth drivers. In 2025, purchasing members grew 26% year-on-year, with customer base expansion solidifying the growth foundation; Gold Card and Platinum/Diamond VIP members jointly support high-end Perfumes & Cosmetics consumption, while standard card members achieve double-digit spending growth; women contribute nearly 80% of Perfumes & Cosmetics consumption; men's gifting and self-use demand is rising, Gen X anti-ageing demand is being released, and lower-tier market consumption willingness is increasing, forming diverse growth drivers.
cdf capitalises on customer base growth drivers, expands potential categories, and actively introduces quality domestic brands; meanwhile, it reinforces premium services through the launch of travel retail exclusive sets, premium beauty centres, and the "S Store" (Super Service) programme.
3.2 Jewellery & Watches
The category exhibits the characteristics of "strong jewellery growth and high watch concentration". In 2025, jewellery, buoyed by gold investment value and women's self-gifting demand, demonstrated strong growth momentum. Watches are dominated by the high-end market with scarcity and value-retention attributes, while the basic watch market is shrinking under the impact of smartwatches.
Gold consumption appeal continues to be released, with classic watches performing steadily. Jewellery, benefiting from the gold consumption boom, became the core of category performance growth, up 16% year-on-year; classic watch brands maintained steady sales, broadly consistent with the industry's "volume down, price up" performance.
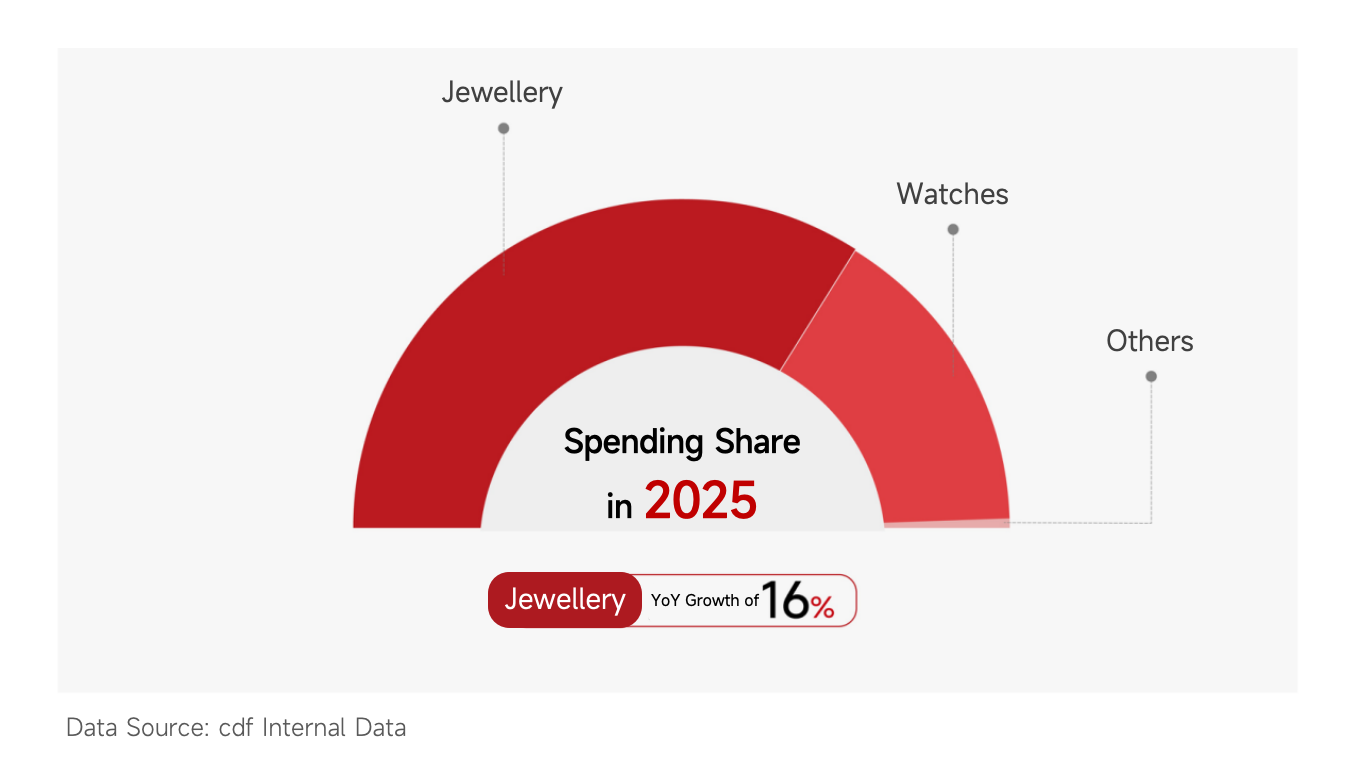
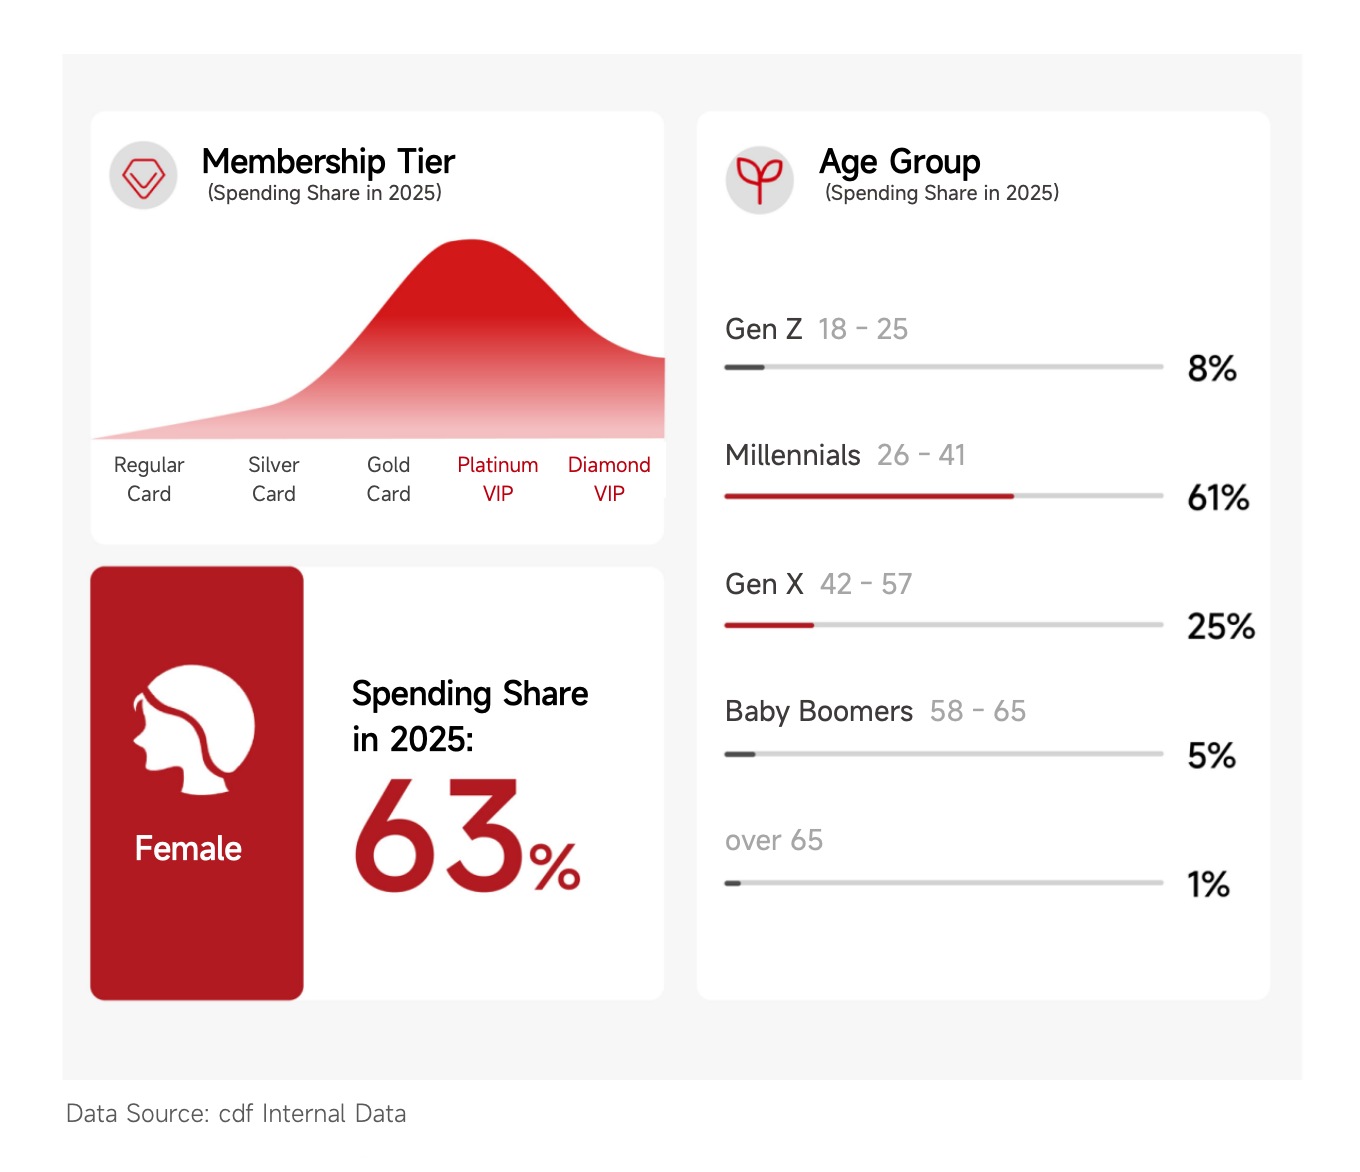
The high-spending member base continues to thicken, with Platinum/Diamond VIP members, women and Millennials as the main consumption force. Members with annual spending of RMB 20,000 and above account for 33%, up 4 percentage points year-on-year; Platinum and Diamond VIP members jointly contribute over 70% of sales, demonstrating the driving effect of refined high-tier member operations on category growth; women and Millennials each contribute 60% of sales; Gen X and above age groups continue to see rising annual spending, with Tier 3 and below cities leading in consumption scale.
cdf deepens cooperation with international high-end jewellery and domestic renowned gold brands in jewellery, launching channel-exclusive co-branded products to capture investment value and self-gifting demand; in watches, it builds a high-end service system through private tasting events and craft master sharing salons, and leverages the "cdf Watch Festival" marketing IP to activate growth momentum across all brands.
3.3 Luxury Goods & Accessories
Luxury growth is mainly driven by stable repeat purchases from heavy luxury customers and the consumption recovery in accessible luxury. As the customer base trends younger, consumption motivation is shifting from social signalling to brand identity and emotional value, driving brand competition to focus on premium services, emotional storytelling and experience innovation.
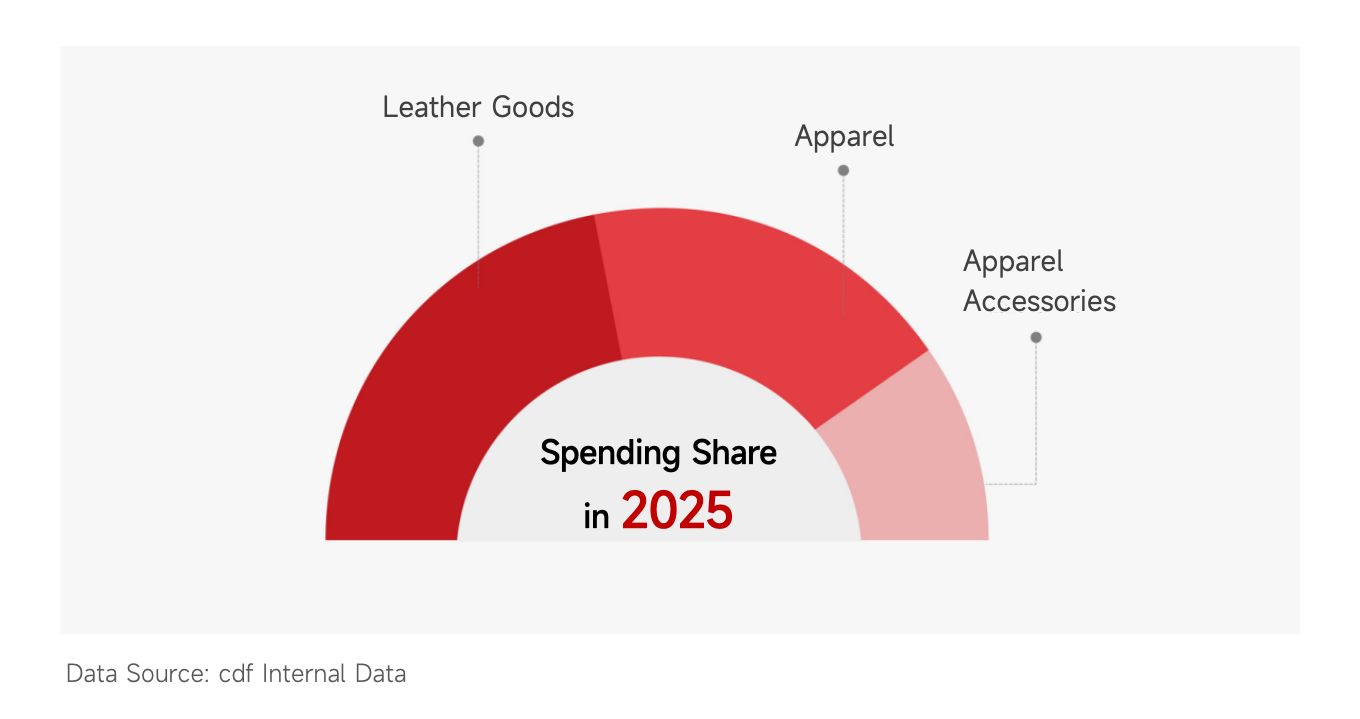
Leather goods and apparel dominate, with heavy luxury steady and accessible luxury recovering. Leather goods and apparel contribute over 80% of sales; classic leather goods and ready-to-wear brands demonstrate stable growth relying on "value retention attributes", while accessible luxury brands show strong growth momentum.
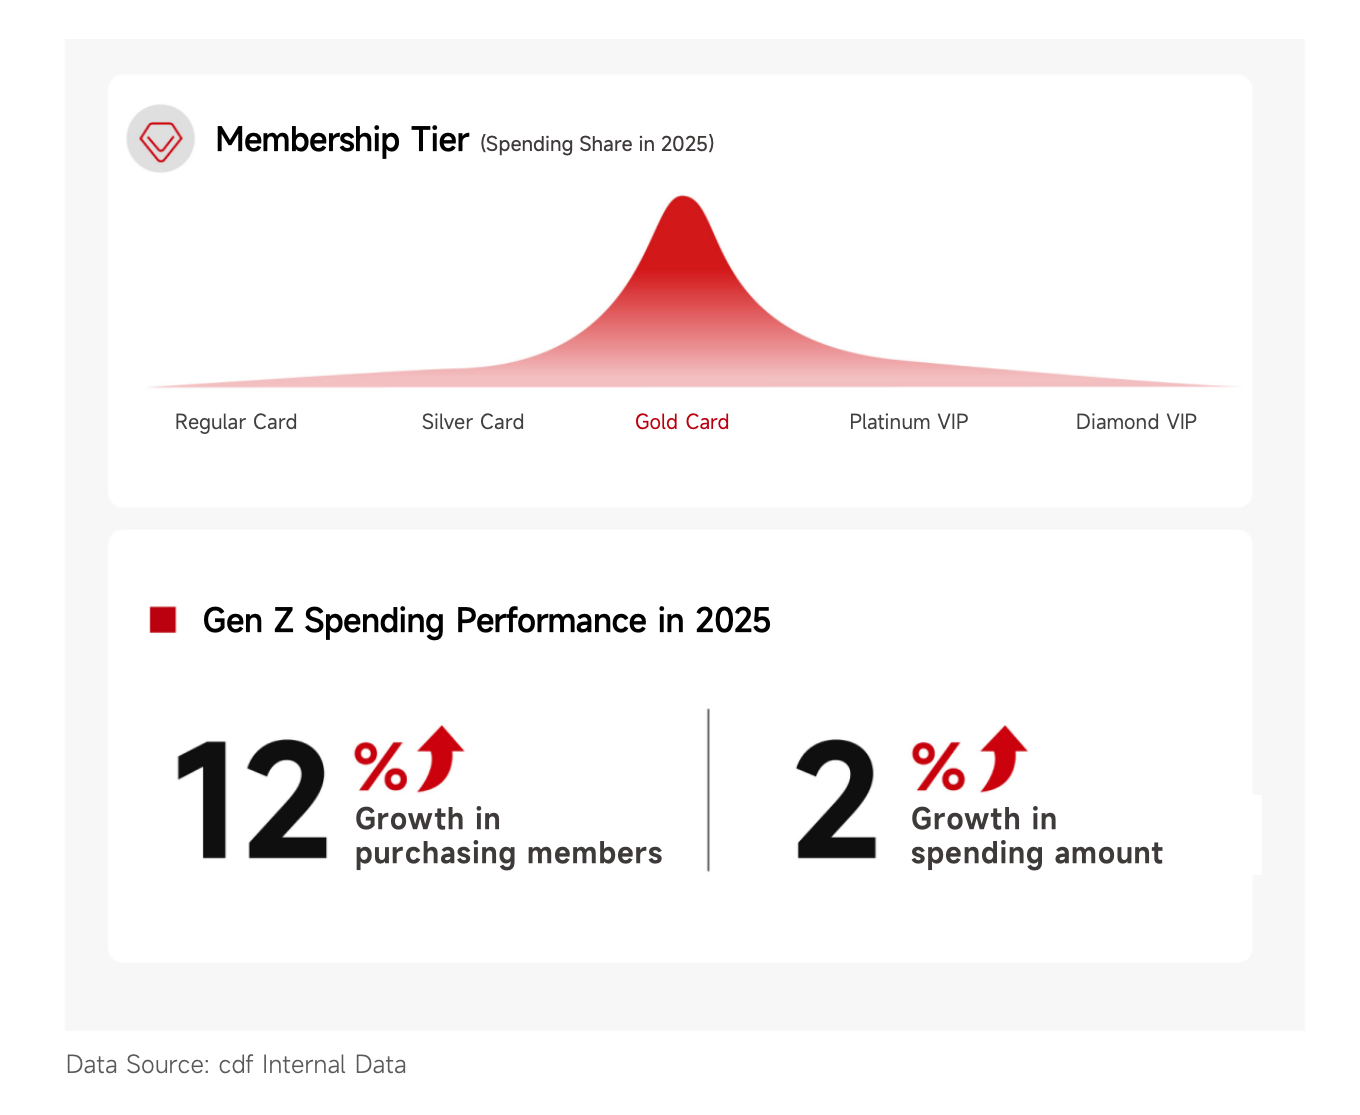
High-tier member value is prominent, with women and Millennials as the main consumption force and Gen Z as the long-term growth foundation. Members with annual spending exceeding RMB 10,000 account for 25%, contributing 71% of category consumption; Gold Card and above members account for over 80% of consumption; women and Millennials account for 68% and 58% of spending respectively; Gen Z is key to long-term category growth, with both purchasing member numbers and spending amount rising.
cdf cooperates deeply with global leading luxury brands, revitalising store layouts with Hainan as the core hub, transforming brand culture into emotional consumption scenarios; meanwhile, online it effectively captures entry-level customer demand by using apparel, accessories and accessible luxury as entry points.
3.4 Food & General Merchandise
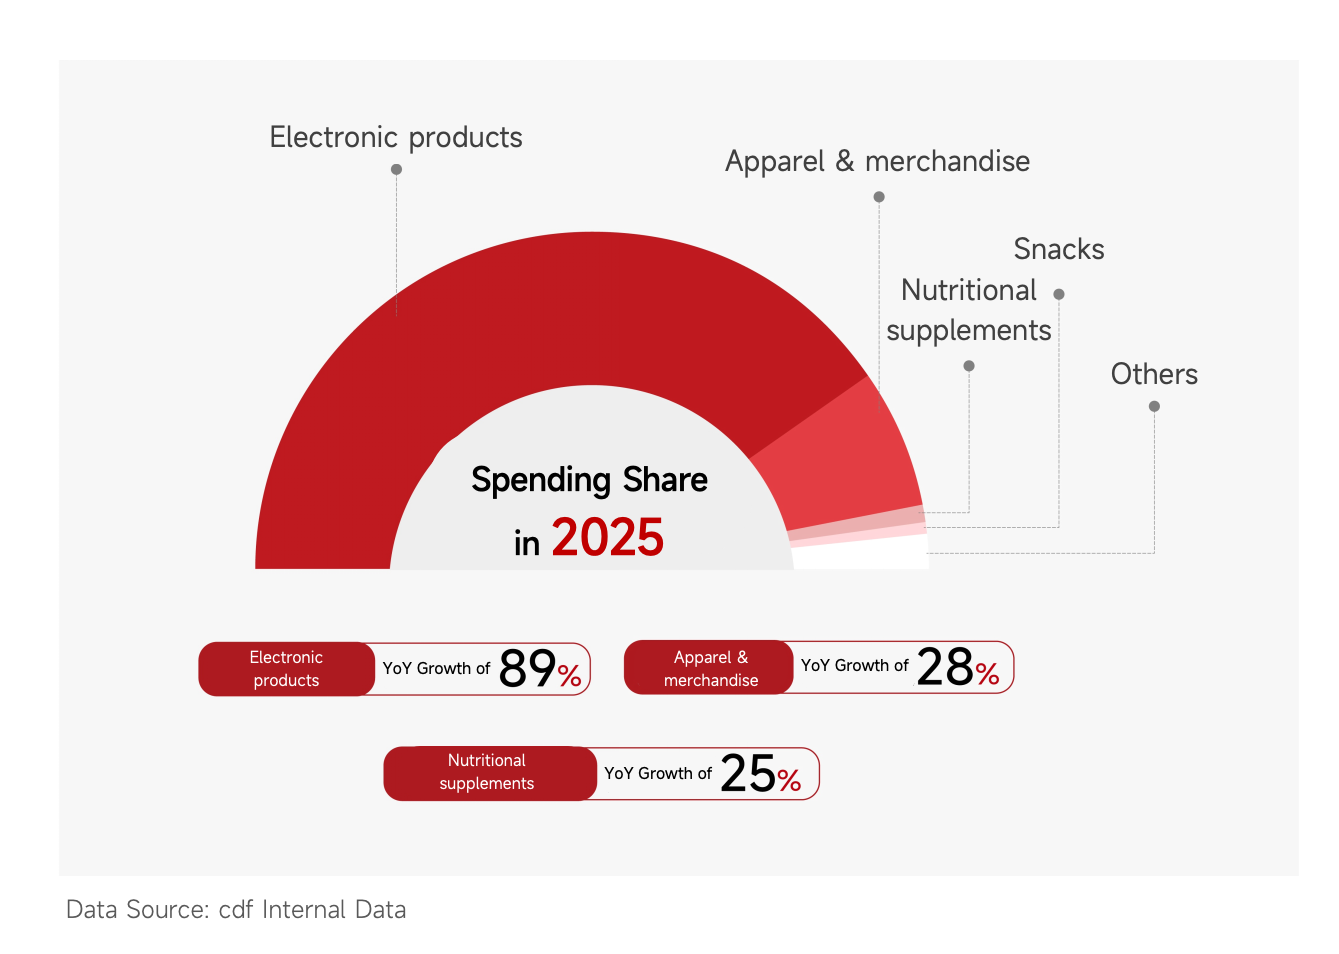
Aligning with the three major trends of smart wearables popularisation, outdoor sports becoming part of daily life, and proactive health management, this category achieved 72% year-on-year spending growth in 2025, with electronics leading and sportswear and nutritional supplements following. The consumer base is driven by Gold Card members and lower-tier markets.
Electronics are the main force, with outdoor sportswear and health supplements steadily releasing growth momentum. Electronics grew 89% year-on-year, with mobile phones and smartwatches as the main hot sellers; apparel/general merchandise and nutritional supplements grew 28% and 25% year-on-year respectively, with mid-to-high-end outdoor brands showing significant growth.
Gold Card members demonstrate both high consumption volume and high growth rates, with lower-tier market consumption potential continuing to be released. Annual purchasing members grew 34% year-on-year, with per-capita spending continuing to rise, up 29% year-on-year; Gold Card members are both the core consumption force and the core engine driving category growth; Millennials and Tier 3 and below city customers constitute the base, with Tier 3 and below city members' annual spending 1.3 times the overall average.
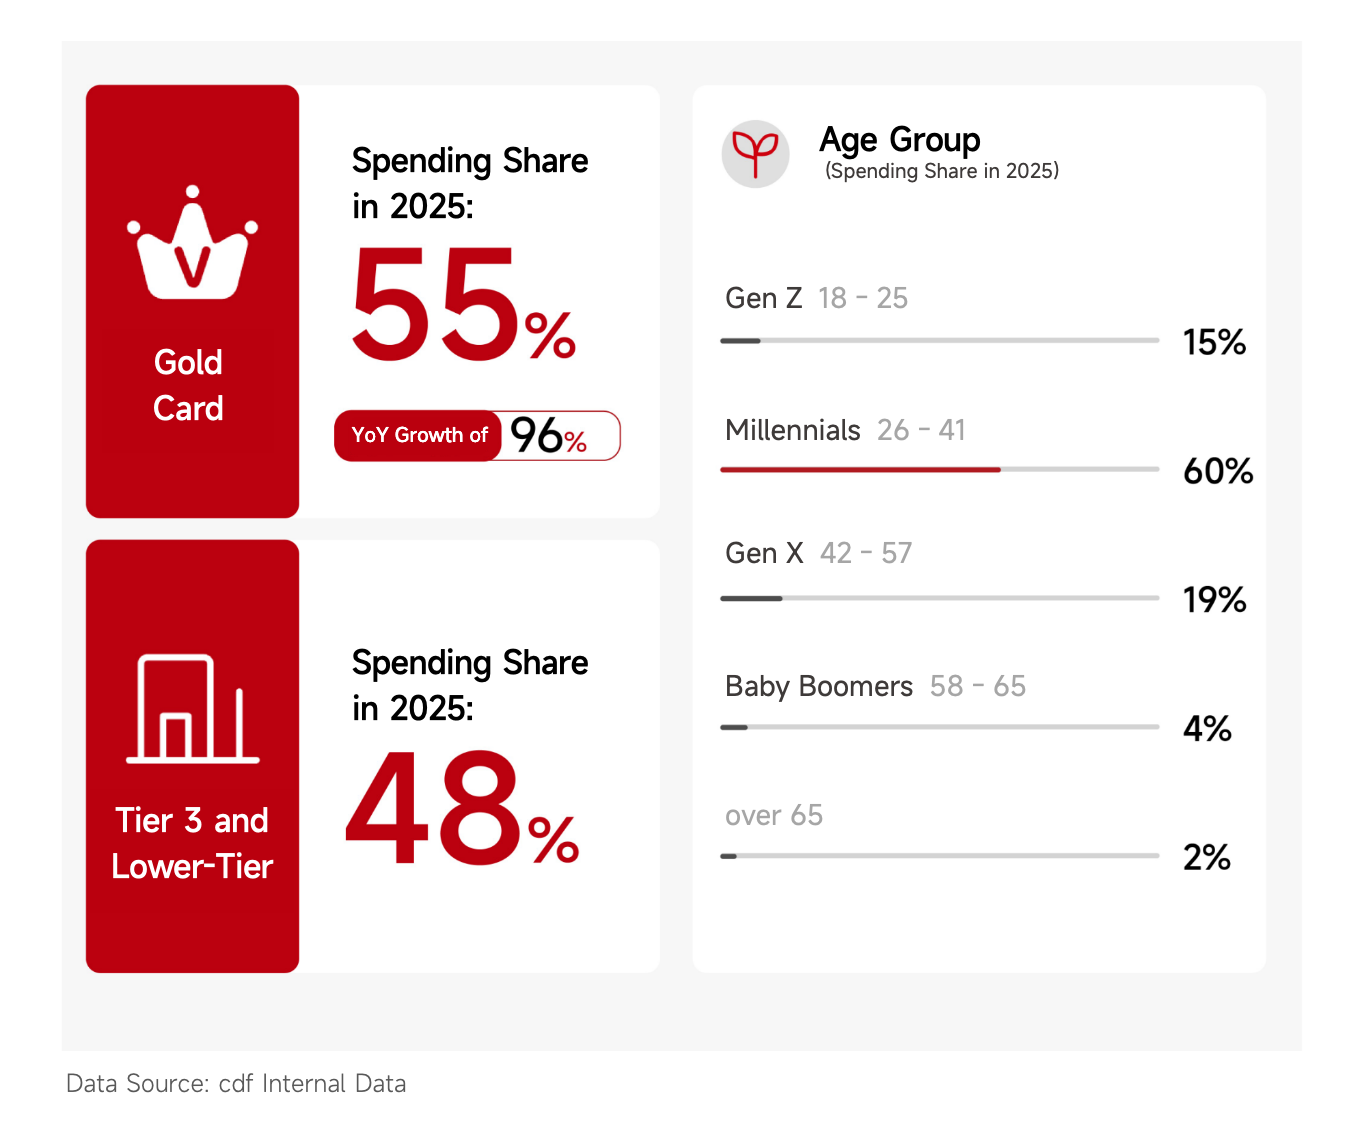
cdf solidifies the electronics base across all domains, fully covering consumers' diversified needs including new device purchases and daily accessory replenishment; it continues to introduce outdoor sports brands and strengthens user brand perception through upgraded brand store images and themed experience activities; it builds a health product matrix relying on private labels and carries out cross-border marketing to expand diversified health consumption scenarios.
3.5 Wines & Spirits
Whisky has achieved growth leadership thanks to the rise of younger and family consumption scenarios. The overall spirits customer base exhibits the characteristics of "high-net-worth men as the anchor, with penetration into younger generation". cdf continuously activates spirits consumption momentum through scarce merchandise introduction, using the "Whisky Museum" as a key lever.
Whisky relies on innovative experiences to achieve outstanding sales growth. Whisky accounts for over 40% of spirits category sales, and with the "Whisky Museum" and "Wei Ni Gan Bei" marketing IP, sales grew 17% year-on-year; domestic baijiu, relying on gifting and collection demand, grew 7% year-on-year.
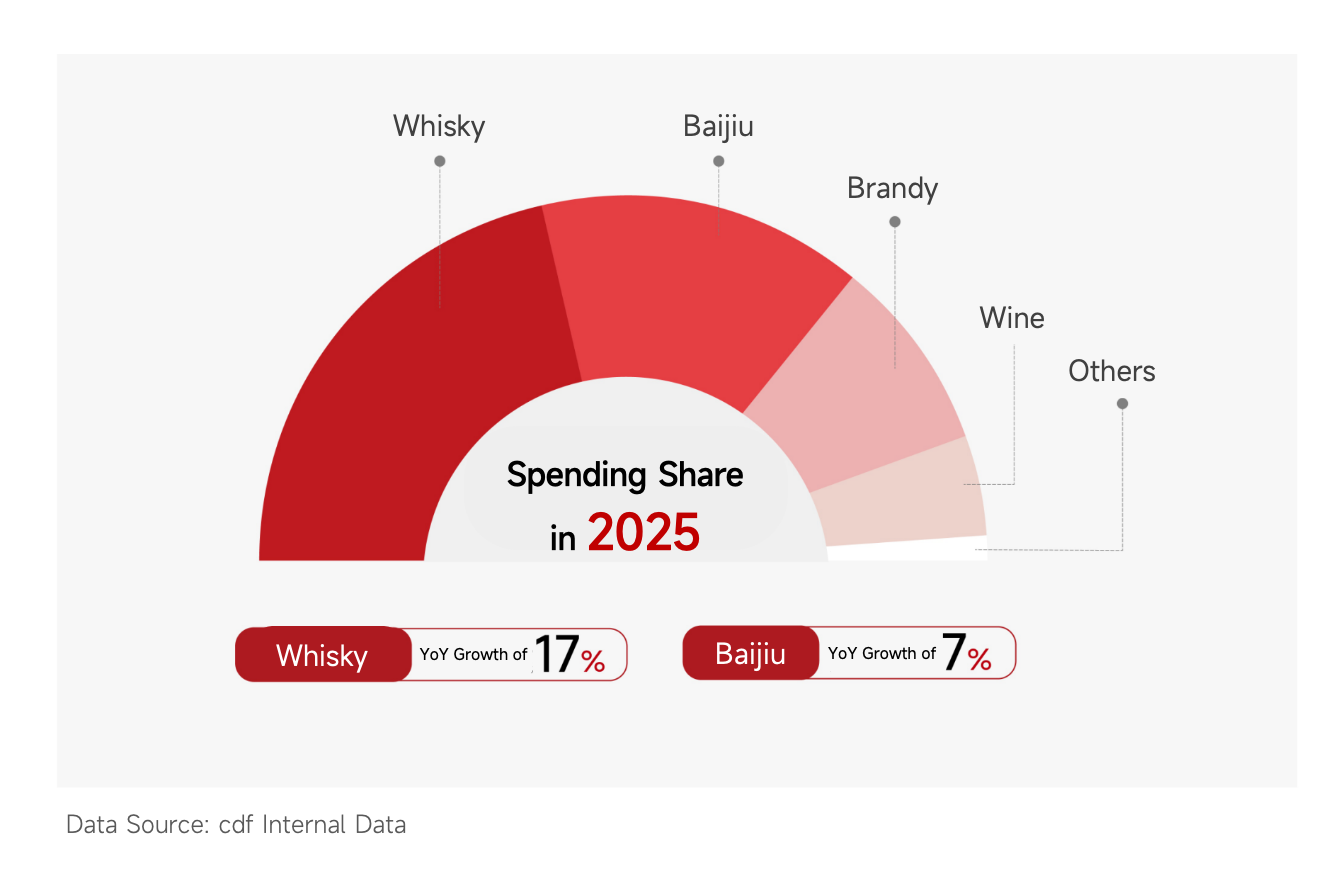
Men dominate high-end spirits consumption, with Millennials and Gen X as the core circles, while Gen Z contributes new growth through low-alcohol flavoured spirits. In 2025, spirits purchasing members achieved 6% year-on-year growth, with innovative operations delivering significant results; the customer base demonstrates outstanding spending power, with Gold Card and above members accounting for 68%; men dominate spirits consumption, with annual spending 1.4 times that of women; Millennials and Gen X are the consumption backbone, jointly accounting for nearly 90% of consumption; Gen Z tends to purchase low-alcohol products or brandy for home cocktail mixing.
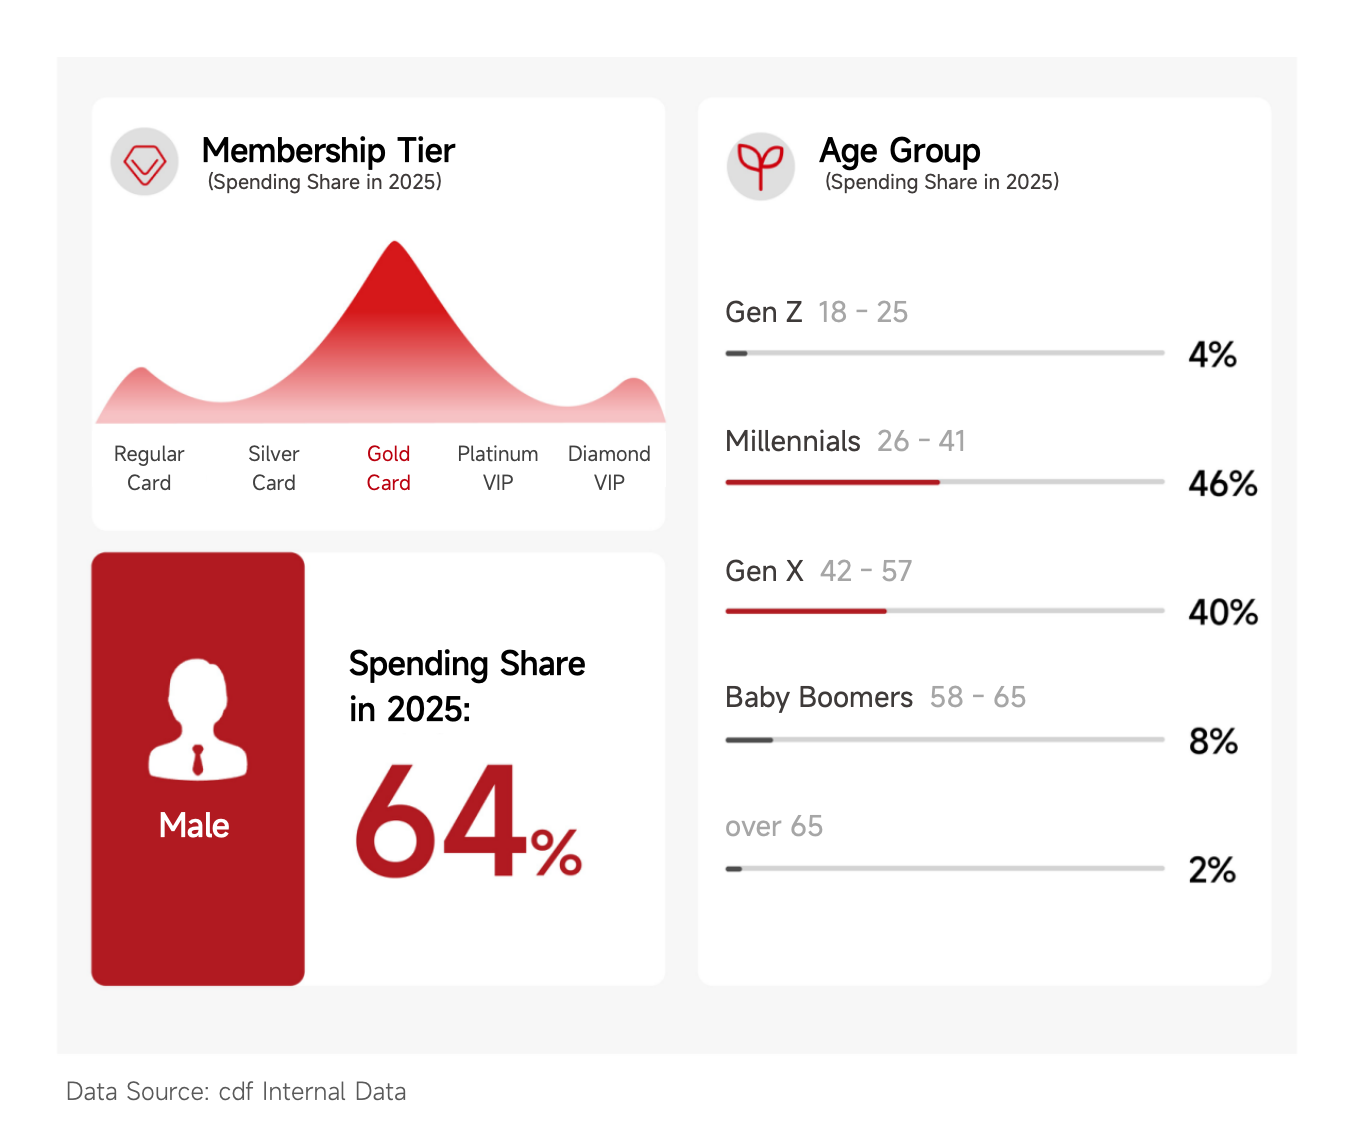
cdf actively competes for new product debuts and exclusive limited editions from high-end spirits brands; meanwhile, it launches the category marketing IP "Wei Ni Gan Bei", lands the "Whisky Museum" and "City Whisky Tipsy Plan", and explores spirits consumption increments in multiple forms.
Chapter 4 | cdf's Omnichannel Layout in Duty-Free and Travel Retail
1. cdf's Core Strengths: Building a Leading Position Through Six Major Advantages
cdf positions itself as a "world-class digital and intelligent travel retail operator". Relying on six core advantages — industry leadership, central SOE backing, omnichannel network layout, refined member operations and omnichannel marketing, complete supply chain infrastructure, and digital and intelligent transformation — cdf commands nearly 80% market share in China's travel retail market.
1.1 Industry Leadership: cdf has held two consecutive Global Brand Conferences, with the 2026 conference attracting 350+ brands, demonstrating cdf's influence in the global travel retail industry.
1.2 Central SOE Backing: The central state-owned enterprise background provides credit endorsement for compliant corporate operations and authentic product guarantee systems, coordinating with the controlling shareholder's full-industry-chain resources to connect travel and duty-free consumption scenarios.
1.3 Omnichannel Network Layout: cdf operates approximately 200 duty-free shops covering nine types including airports, downtown, border ports and cruise ships, and conducts online platform sales.
1.4 Refined Member Operations and Omnichannel Marketing: cdf has built in-depth, refined full-lifecycle member operations, with proprietary channel system business coverage reaching 90%; in addition, cdf has developed multiple iconic annual marketing IPs, forming an omnichannel marketing system covering pre-trip, on-trip and post-trip.
1.5 Complete Supply Chain Infrastructure: cdf maintains partnerships with more than 1,600 renowned global brands, and operates eight customs-supervised logistics centres.
1.6 Digital and Intelligent Transformation: cdf has built a large-scale data asset pool, empowering precision marketing; and is building a digital and intelligent supply chain system to optimise merchandise fulfilment.
2. cdf's Channel Layout: Building an Omnichannel Network Covering Domestic and Overseas, Online and Offline
cdf takes Hainan offshore duty-free as the core hub, and coordinates with airport duty-free, downtown duty-free shops, online platforms, and Hong Kong, Macao and international stores to form a multi-layered channel layout. In 2025–2026, cdf achieved major breakthroughs in its channel layout: winning duty-free concession operations at core hub airports in Shanghai, Beijing and Guangzho,downtown duty-free shops have opened in 13 major cities, including Beijing and Shenzhen, achieving steady operations., and acquiring DFS's Greater China retail business in March 2026.
2.1 Hainan Offshore Duty-Free: cdf Deepens the Hainan Market, Building an Industry Benchmark Through Comprehensive Advantages
■ Store Side:
cdf operates 6 offshore duty-free shops, with the Haikou and Sanya International Duty Free Cities ranking among the top two globally by floor area; the Sanya International Duty Free City has been approved as a national 4A-level scenic area. It simultaneously deepens online-offline integrated development and expands duty-paid scenarios, forming a differentiated and complementary all-format store network.
■ Customer Side:
Middle-class customers: are offered children's play areas, childcare services and VIP Lounge.
Business customers: are offered exclusive exhibition discounts, customised vouchers and shuttle services, connecting exhibition and shopping scenarios.
Young customers: are offered the traffic value of the "ticket-stub economy", relying on concerts and sports events for precise traffic acquisition.
Senior "snowbird" customers: supported with upgraded offline health store formats and linkage with local medical institutions for health value-added services.
Island residents: are served with daily consumer goods duty-free shops relying on the customs closure policy.
Foreign customers: offered Guochao souvenirs and continuously optimised multi-language services.
■ Category Side:
A multi-category coordinated growth pattern of "Perfumes & Cosmetics as the anchor, luxury goods revitalising, gold gaining momentum, electronics leading, outdoor sports rising, and spirits upgrading" has been formed.
■ Marketing Side:
cdf has built an all-domain cooperation ecosystem covering hotels, airlines, OTAs, banks, scenic spots and travel agencies, achieving pre-trip targeted traffic acquisition, on-trip store-visit conversion enhancement, and post-trip tiered operations driving repeat purchases. Meanwhile, relying on super-large commercial carriers, cdf creates immersive consumption spaces, deepens the "duty-free + cultural tourism" model, and efficiently converts cultural tourism activity traffic.
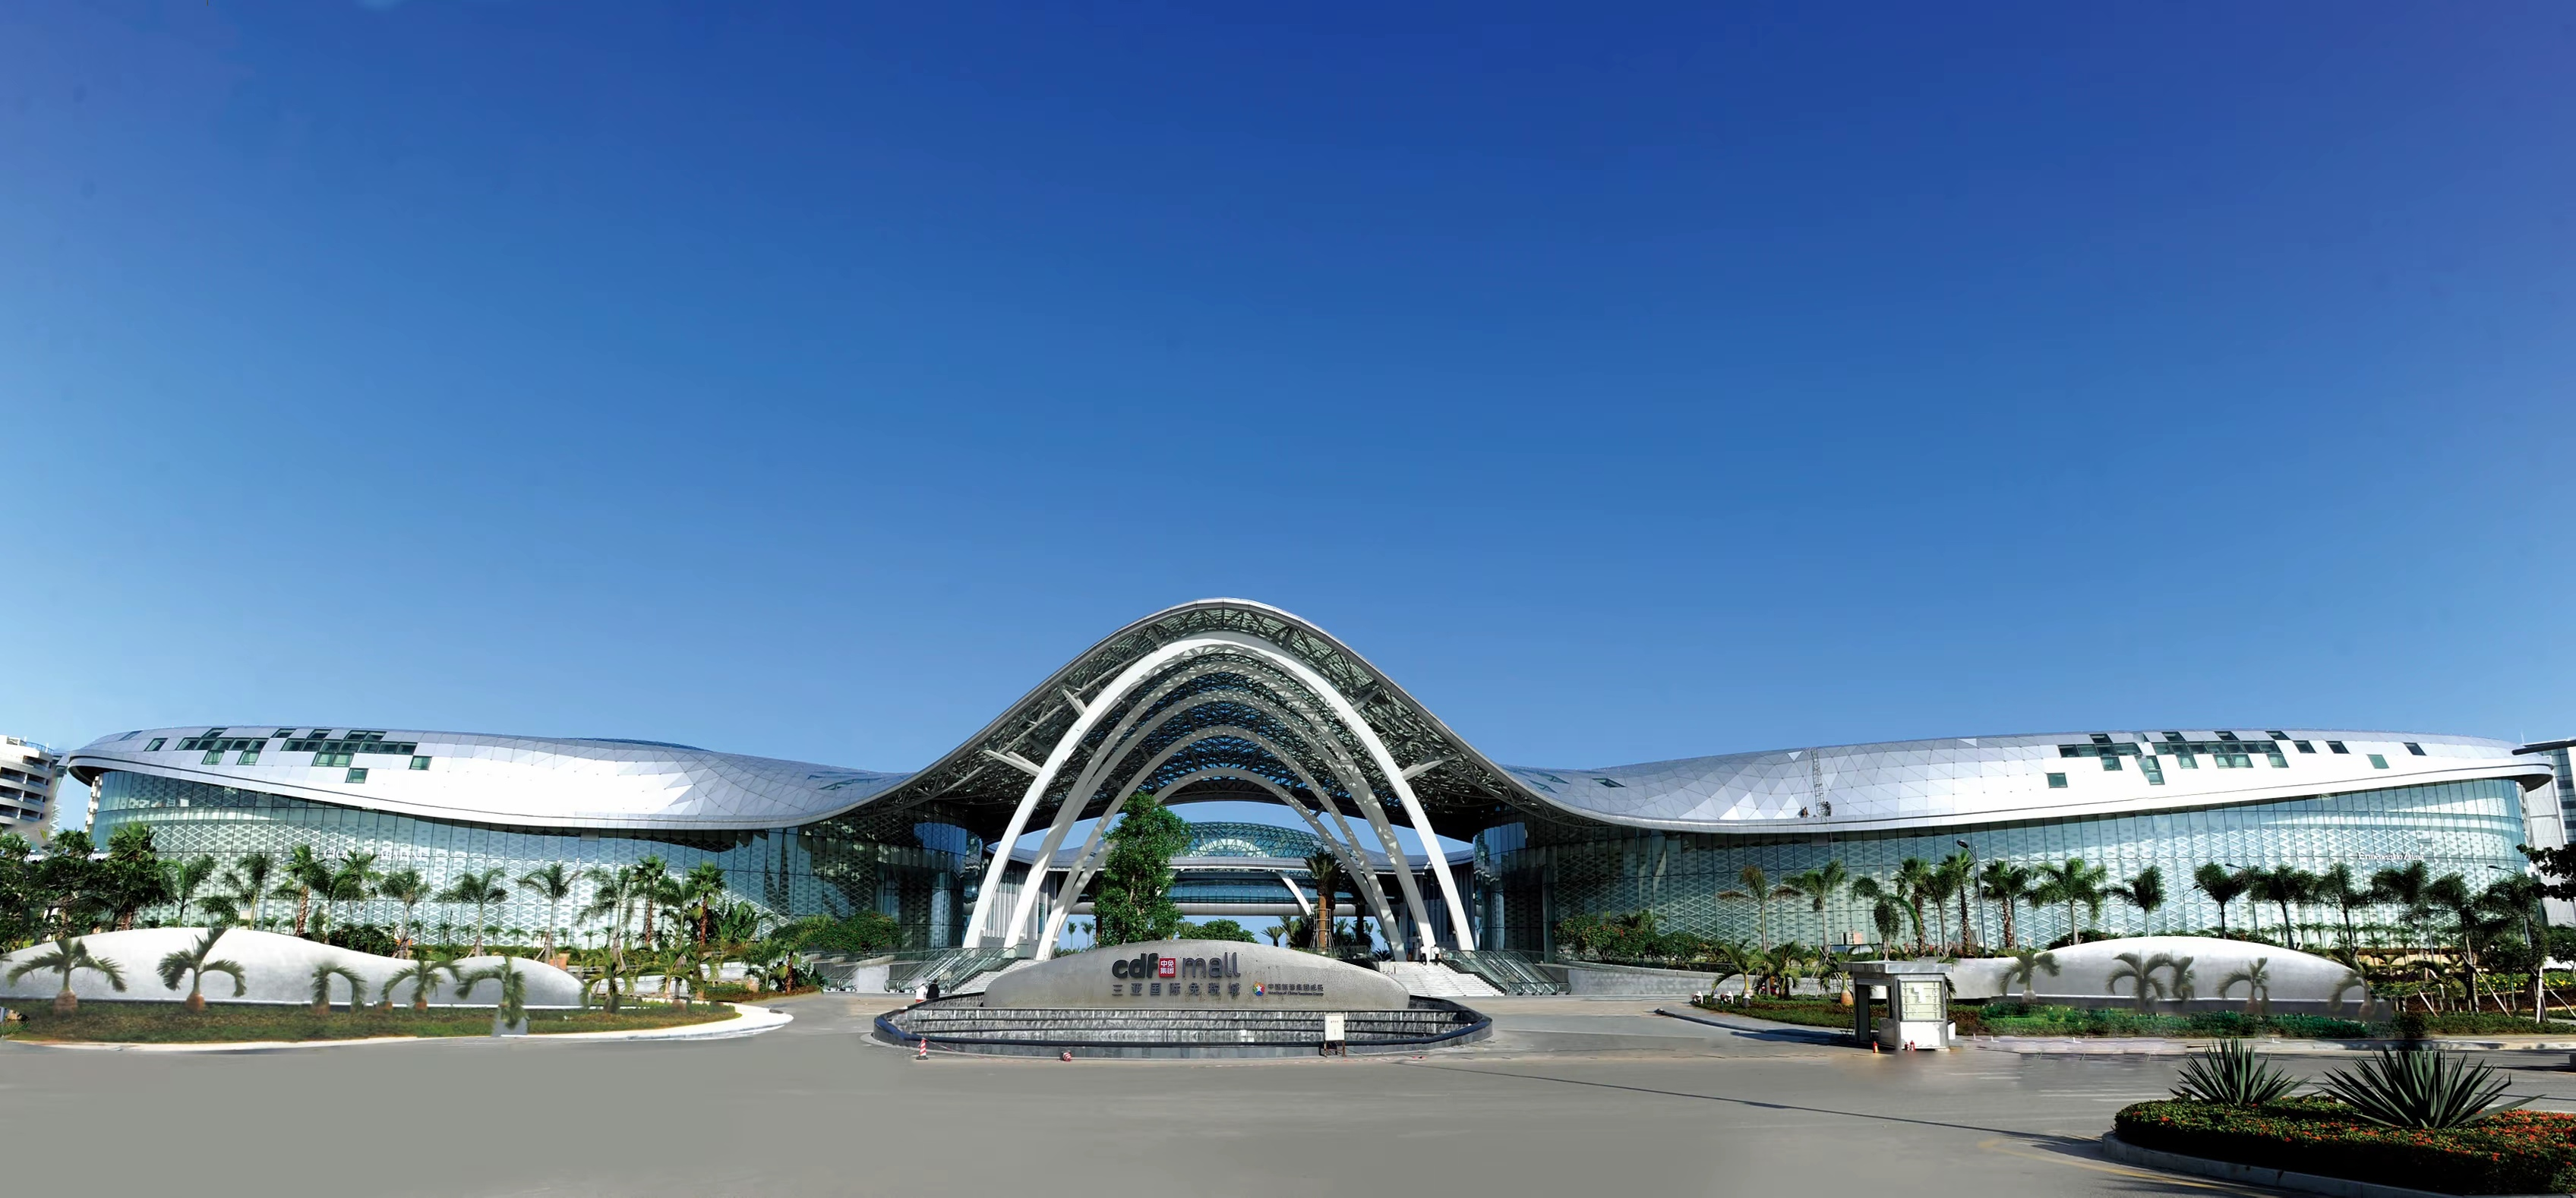
cdf Sanya International Duty Free Shopping Complex
2.2 Airport Duty-Free: Winning Core Hub Concession Operations, Innovating Airport Business Operating Models and Creating a Consumption Atmosphere with Distinctive Oriental Characteristics
■ Store Side:
cdf has secured duty-free concession operations at core hub airports in Beijing, Shanghai and Guangzhou, advancing store renovation and merchandise matrix expansion; in addition, it has built the Lanzhou Airport benchmark project, constructing an integrated commercial system of duty-free, duty-paid retail and characteristic dining.
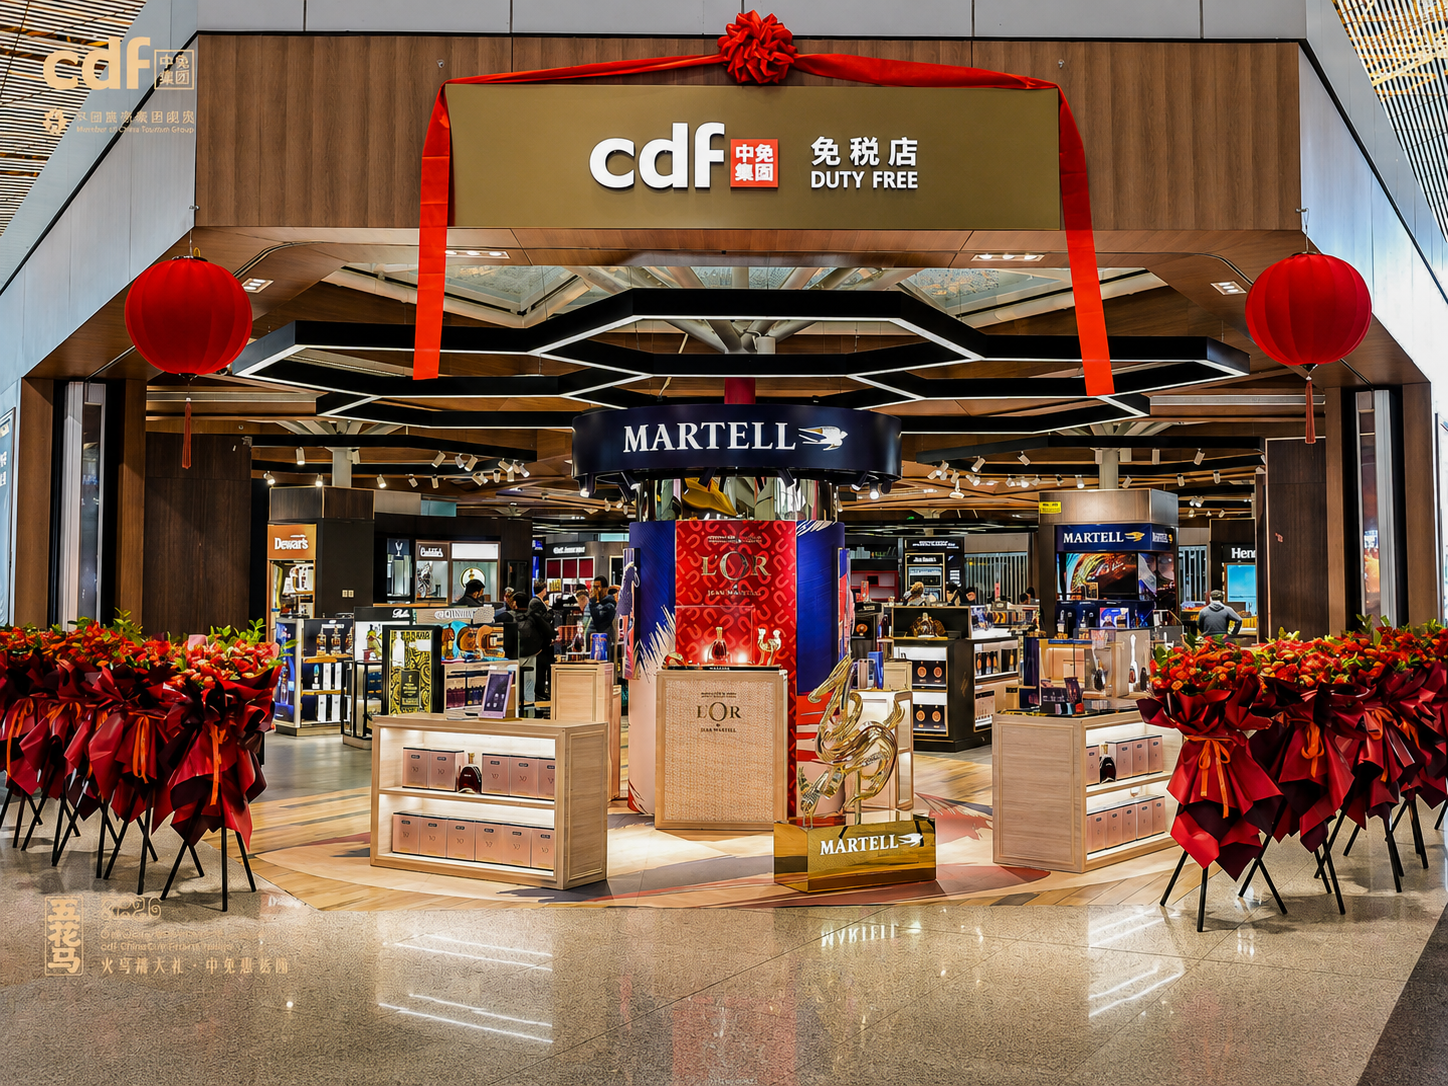
cdf Beijing Capital International Airport Duty Free Shop
■ Customer Side:
Chinese travellers are the main force, while affected by city tier, route network and cultural tourism resources, customer profiles vary significantly across airport duty-free shops.
■ Category Side:
Perfumes & Cosmetics remains the core consumption category for airport duty-free, and with inbound foreigners reaching a record high, Guochao cultural creativity, famous domestic liquors and high-end jewellery blending Oriental cultural elements are achieving rapid growth.
■ Marketing Side:
cdf deeply binds with travel scenarios, relying on peak travel seasons and business activities such as exhibitions to launch "scenario experience + limited-time promotion" combination measures, such as the Beijing Capital International Airport duty-free shop launching a "cooling service" during the summer and combining it with spend-and-save promotions.
2.3 Downtown Duty-Free Shops:
Relying on Policy Support for Store Expansion, with "Duty-Free + Duty-Paid" Coordinated Operations
■ Store Side:
Downtown duty-free shops in 13 major cities, including Beijing and Shenzhen, have fully
opened and are operating steadily. Each shop operates the "duty-free and duty-paid",
"offline+online", and "imported+domestic" models, and carries out departure tax
refund services
to stimulate inbound consumption.
■ Customer Side:
The duty-free zone serves travellers holding outbound credentials within 60 days
(including Mainland Chinese residents, Hong Kong, Macao and Taiwan residents, and foreign
travellers); the
duty-paid zone is open to all (foreign and Hong Kong, Macao and Taiwan residents can enjoy
departure tax
refund), and outbound travellers can simultaneously purchase duty-paid merchandise.
■ Category Side:
Stores take high-end Perfumes & Cosmetics as the core pillar, while simultaneously
expanding domestic beauty and electronics; in addition, they launch products with city recognisability
combining
local culture and characteristic industries, such as Shenzhen downtown duty-free shop focusing on tech
and digital
products, Xiamen downtown duty-free shop delving into sports and trendy products, and Xi'an
downtown duty-free
shop launching city IP cultural creativity products.
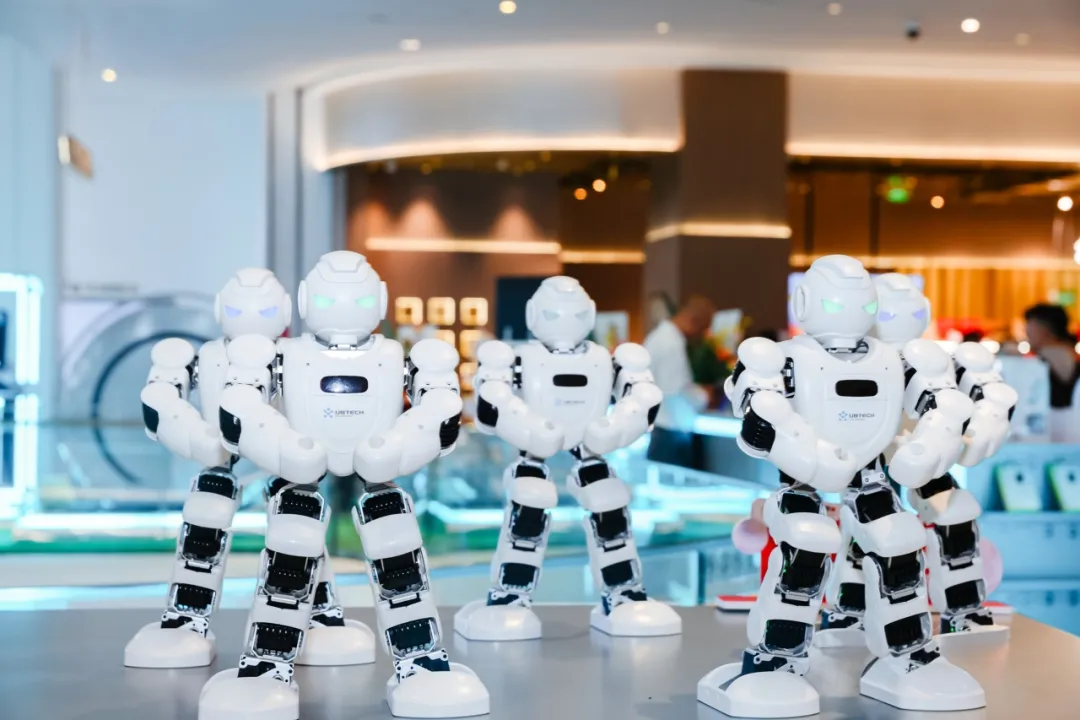
cdf Shenzhen Downtown Duty Free Shop Tech Experience Corridor
■ Marketing Side:
cdf creates regional cultural consumption spaces, combining seasonal promotions to achieve sales growth: Guangzhou downtown duty-free shop integrates "Flower City" elements into spatial design, while Qingdao and Dalian downtown duty-free shops create exclusive shopping experiences for holidays such as Mother's Day, forming a marketing approach of "one city, one feature; one festival, one theme".
2.4 Online Platforms: Solidifying Online Service Capabilities Through Service Scenario Expansion and Resource Synergy
■ Platform Side:
cdf has built and operates three major e-commerce platforms: cdf Mall focuses on offshore duty-free, cross-border selection and member premium selection; at the same time, it actively extends the service chain, launching flash delivery services to meet consumers' instant shopping needs. Different from cdf Mall's positioning, cdf Member Shop is an innovation testbed for category IPs and digital operations, while cdf Sunrise deepens its focus on Perfumes & Cosmetics through digital upgrades and content construction.
■ Customer Side:
cdf Mall's core customer base consists of offshore travellers with offline duty-free consumption behaviour, mainly covering leisure tourism and business travel groups; cdf Member Shop gathers a large number of spirits enthusiasts, while cdf Sunrise focuses on women in the Jiangsu-Zhejiang-Shanghai region.
■ Category Side:
Perfumes & Cosmetics remains the sales base for all three platforms, with each platform implementing differentiated category layouts: cdf Mall sees domestic beauty and health categories becoming new growth drivers; cdf Member Shop features spirits; cdf Sunrise actively expands 3C digital, men's care and health categories.
■ Marketing Side:
cdf Mall builds a closed-loop marketing system covering pre-trip, on-trip and
post-trip, strengthening full-lifecycle user operations; cdf Member Shop advances featured digital
marketing
projects such as celebrity store visit livestreams; cdf Sunrise deploys online content
communities.
2.5 Hong Kong, Macao and International: Expanding Overseas Shops and Acquiring DFS's Greater China Retail Business to Continuously Strengthen Global Operating Capabilities
■ Store Side:
In the Hong Kong and Macao markets, cdf achieves multi-scenario layouts covering port
crossings, landmark business districts and integrated resorts through self-operated store expansion and
the
acquisition of DFS Hong Kong and Macao stores. In the Southeast Asian market, it enters Vietnam
airports
through a light-asset cooperation model, continues to deepen localised operations at Cambodian stores,
and explores
single-brand boutique models at Singapore airports.
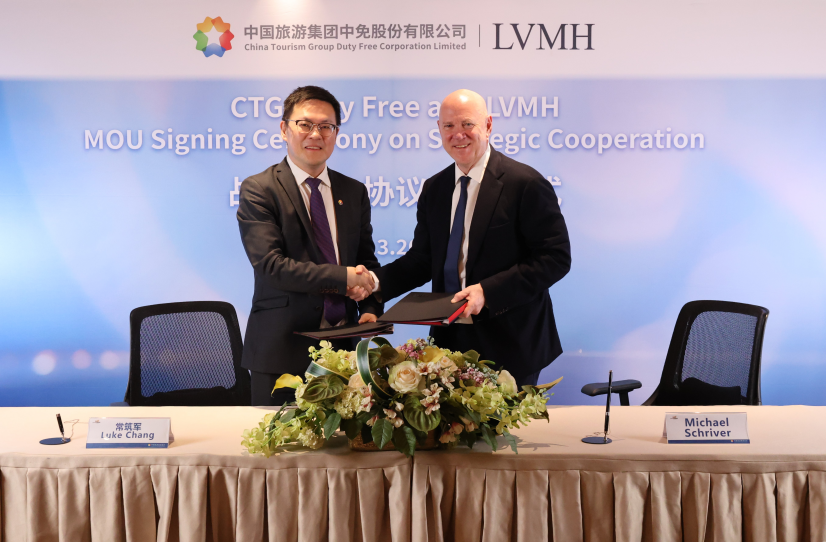
China Duty Free Group, DFS Group and LVMH Group Signing Ceremony
■ Customer Side:
Southeast Asian and Russian tourists are growing significantly. cdf actively captures
port hub traffic and further expands the foreign customer base through measures such as securing local
consumption
policies and building multi-language overseas member service systems.
■ Category Side:
Perfumes & Cosmetics, spirits and high-end jewellery are the core consumption
categories. cdf optimises domestic brand operations relying on localised teams; meanwhile, it builds a
full-chain,
self-developed cultural creativity system, with the first batch of Cantonese dim sum culture dolls
achieving
strong sales across multiple channels in Hong Kong, China.
■ Marketing Side:
Breaking through the boundaries of traditional store services, for high-end customers
at Hong Kong and Macao stores, cdf delivers a high-end service system through hyper-personalised
service
solutions, scarce merchandise supply, deep emotional value connection and comprehensive privacy
protection.
Chapter 5 | Outlook for the Duty-Free and Travel Retail Market
In 2025–2026, China's duty-free and travel retail industry stands at a critical juncture connecting the past and the future. The implementation of a series of policies and the upgrading of consumer demand are driving China's duty-free and travel retail industry from "traffic-driven" to "value-driven".
Global Recovery Is Broadly Established, and the Chinese Market Holds Prominent Growth Advantages
The global duty-free and travel retail market is on an upward trajectory, and the Chinese market, relying on policy dividends such as Hainan's customs closure operation and the new offshore duty-free policy, combined with inbound passenger traffic growth, has formed outstanding growth advantages.
Consumer Spending Presents Three Major Trends: Structural Divergence, Experience Upgrading, and Intelligent Decision-Making
The consumer base is exhibiting three major changes: first, structural divergence of the customer base, where homogeneous services are no longer sufficient to match diverse needs, and cdf is advancing refined operations through differentiated service systems; second, offline experience demand is becoming prominent, with stores accelerating upgrades toward composite spaces combining shopping, socialising, leisure and experience; third, consumers are relying on AI tools to complete product comparison and review analysis, and travel retailers are accelerating the integration of AI tools into the consumption decision-making process.
Category Operations: Shifting from Product to Service-Value Competition
Travel retailers are enriching their supply systems through potential category expansion, scarce merchandise introduction and private label incubation. When category layout tends toward completeness, category service value will become the core barrier, with brand supporting services and immersive category experience space creation becoming the focus of competition.
Channel Competitiveness: Reshaped by Scenario Synergy, Format Innovation, and International Expansion
Channel operations are comprehensively upgrading from single sales to scenario-based integration: Hainan offshore duty-free deepens the "duty-free + cultural tourism" format integration, airport duty-free shops are gradually transforming toward integrated commercial spaces, downtown duty-free shops carry out differentiated layouts around city characteristics, and online channels form complementary linkage with offline stores. Meanwhile, leading enterprises are accelerating overseas layout, expanding global customer bases and supporting Guochao Going Global.
Conclusion
cdf builds its foundation on a 62-million-member base and an omnichannel network. Remaining fully focused on its core duty-free and travel retail business, the group delves deep into member operations, category innovation and shopping scenario upgrades, powered by digital intelligence as its core engine to advance the industrial shift from broad traffic coverage to intensive value mining.
cdf's vision goes beyond becoming a world-class digital and intelligent travel retail operator. It aims to serve as a bridge linking global brands with Chinese consumers, as well as a cultural window showcasing China's consumer culture to the world. Upholding its mission of "Brimming with the World's Best", cdf will collaborate with global partners to jointly shape a new future for the industry.
To read the full report, please click to download: